DE

Important facts
- Are used goods generally affected by the EUDR?
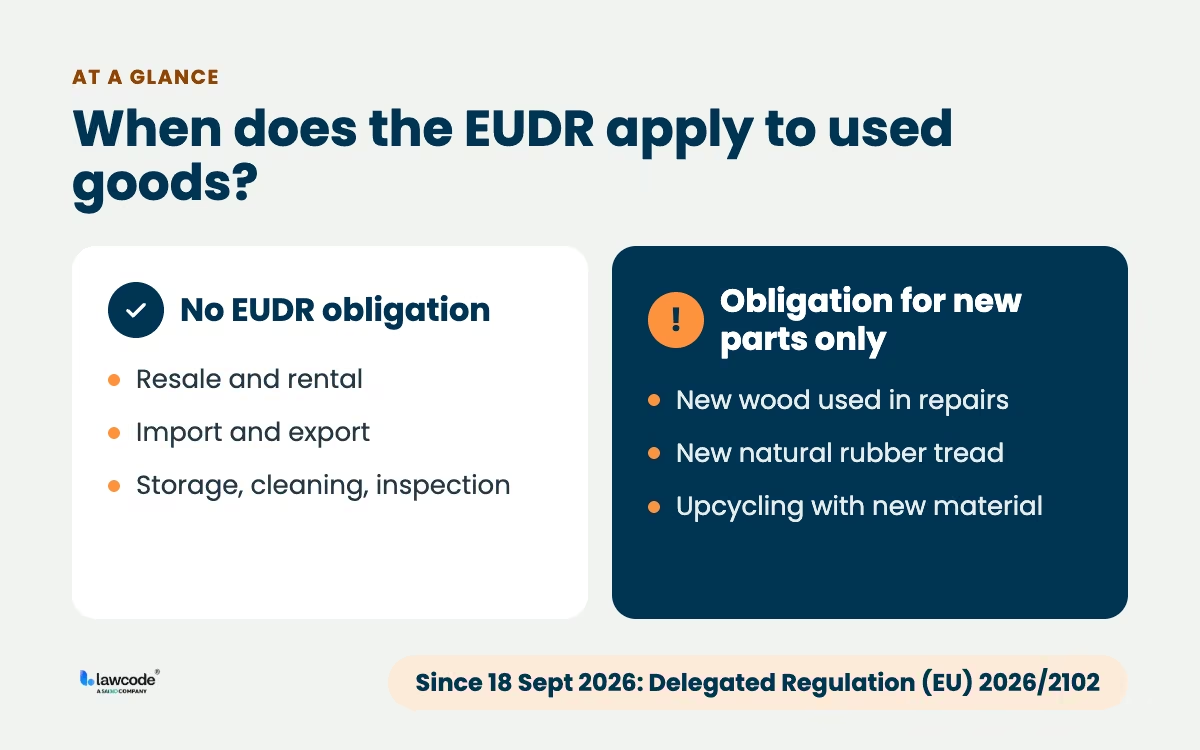
- In most cases, no. Delegated Regulation (EU) 2026/2102 excludes used and secondhand products from most wood, furniture, and rubber items listed in Annex I. The wording of the respective entry in Annex I is decisive.
- When can used goods still be subject to EUDR?
- As soon as new material subject to the EUDR is added, such as new wooden parts on pallets or a new tread on tires, the obligations apply only to that new material, not to the entire product.
- What is considered a "significant change"?
- “Substantial change” is not a term defined in the EUDR, but rather a working term used in practice. The key factor is whether new, relevant material is incorporated. Cleaning, maintenance, or minor repairs that do not involve new material do not trigger any obligations.
- What documentation is useful for used goods?
- Proof of purchase date, origin, serial numbers and maintenance history are recommended in order to be able to fully document the used status.
- Do exports of used goods outside the EU have to be checked?
- No, provided the goods have not been significantly modified, no new EUDR inspection is required for export.
- What should companies bear in mind when dealing with used EUDR-relevant products?
- Clear labeling of the used status and transparent communication along the supply chain, in invoices, delivery bills or digital systems are crucial.
Executive Summary
The EUDR requires proof before certain products are placed on the EU market for the first time: The raw materials they contain must be legally sourced and deforestation-free. To this end, market participants submit a due diligence statement, while downstream traders are only required to maintain certain information. Non-SMEs must also register in the EU information system.
The EUDR does not apply to most used goods. Delegated Regulation (EU) 2026/2102, in effect since September 18, 2026, excludes used and secondhand products from most wood, furniture, and rubber items listed in Annex I. This also applies to pallets and used tires. Obligations arise only when new EUDR-relevant material is added, and then only for that new portion, in the case of retreaded tires, for the new tread.
If new EUDR-relevant material is introduced, this constitutes a substantial change. Examples include replacing load-bearing wooden components on pallets or retreading tires with fresh natural rubber. The EUDR requirements then apply only to the new components, in the case of tires, this means the new tread.
Companies should therefore thoroughly document the origin of their products and record the reference numbers of the due diligence statements for new components. Clearly labeling new and used goods throughout the supply chain significantly reduces regulatory risk.
Never miss an update on the EUDR again.
New specialist articles, regulatory updates and practical tips, straight to your inbox. Once a week, no spam.
Does the EUDR apply to used products?
The EUDR does not apply to most used goods. The European Commission clarified this in Delegated Regulation (EU) 2026/2102, which has been in effect since September 18, 2026. For companies, however, this does not settle the matter, because in practice, the key question is: When is a product still considered used, and when does it contain new material that falls under the EUDR again?
What counts as a used item? For the purposes of this article, a used or secondhand item is defined as an item that has already been used by a consumer and is being resold, rented, or reused.
The trade in used goods has a long tradition in Europe and is becoming increasingly important due to resource scarcity and sustainability goals. Tires, containers, and shipping pallets often go through multiple cycles of use. They are repaired, refurbished, or fitted with new parts and then resold. This is precisely where the difficulty lies: A pallet that is resold unchanged poses no problem. A pallet whose load-bearing wooden components have been replaced contains new EUDR-relevant material and triggers obligations once again for those components.
Added to this is a problem with documentation. Many companies have inventory for which only incomplete information is available, especially if the products entered the EU years ago. It is often nearly impossible to prove when a product was first placed on the market. Those who cannot document this will have a hard time actually claiming the exemption for used goods in cases of doubt.
Does the exception apply to all products listed in Annex I? No. The exception for used goods is not a general rule, but rather appears as the addition “except used and secondhand products” in the individual entries of Annex I. It can be found in almost all wood headings from 4401 to 4421, including pallets (4415), as well as in many furniture and rubber headings. Companies should therefore check for each tariff code to see if the entry includes this addition. In general, however, waste as defined by the Waste Framework Directive 2008/98/EC is excluded.
Which products does the EUDR actually cover?
The EUDR covers seven raw materials and the products made from them, which are listed in Annex I: cattle, cocoa, coffee, oil palm, rubber, soy, and wood. These include, for example, furniture, paper products, and tires made from natural rubber. Here you can find an overview of the EU Deforestation Regulation.
In the EU, only products that are deforestation-free and legally produced may be placed on the market, made available, or exported. A mere assurance is not sufficient. Companies must provide verifiable evidence of deforestation-free production: trace the origin of raw materials, verify compliance with local laws, issue a due diligence statement, and keep supporting documentation on hand.
The content of Annex I was also amended by Delegated Regulation (EU) 2026/2102. Items removed include, among others, bovine hides and leather, conveyor belts and drive belts, as well as aircraft and motor vehicle seats. Retreaded tires are now covered only if they have a new tread.
When is a product considered to have been “placed on the market”?
Placing on the market refers to the first time a relevant raw material or product is made available on the EU market (Art. 2(16) of the EUDR). It does not matter whether the item is a raw material, a component, or a finished product. The only decisive factor is when it is placed on the market for the first time.
Once a product has been lawfully placed on the market in the EU, it remains so. Resales, changes in ownership, rentals, or storage within the EU do not trigger a new obligation to test the product. If, on the other hand, a product is imported from a third country for the first time after the date of application, this is generally considered to be the first placing on the market. For used and secondhand products, the Delegated Regulation (EU) 2026/2102 has extended this exemption to imports as well, provided that the relevant entry in Annex I so provides.
Delegated Regulation (EU) 2026/2102 was published in the Official Journal on September 17, 2026, and entered into force on September 18, 2026.
What was the law before the Delegated Regulation?
Prior to Delegated Regulation (EU) 2026/2102, the exemption for used goods was narrowly defined. It applied only to products that had reached the end of their life cycle and would otherwise have been disposed of as waste (Art. 3(1) of the Waste Framework Directive 2008/98/EC). A five-year-old pallet that was still being traded was therefore not considered waste and did not fall under the exemption. It was unproblematic only because it was already on the market before the regulation took effect. As of September 18, 2026, this distinction no longer applies to items labeled as “used goods.”
Update on Legal Status: Regulation (EU) 2025/2650
The EUDR clearly distinguishes between two roles. Market participants who place a product on the market for the first time bear full due diligence responsibility. Downstream market participants and distributors merely pass a product on. They generally do not submit a due diligence statement and are not generally required to verify whether their upstream suppliers have fulfilled their due diligence obligations.
However, they are not entirely exempt from obligations. Companies that are not SMEs must register in the EU information system. In addition, these companies may only trade in, make available, or export relevant products if they collect and retain the required information.
When do used goods typically not trigger a new EUDR obligation?
Products that were already placed on the market in an EU member state before the EUDR took effect are not subject to re-evaluation, even if they are resold, leased, or exported. The EUDR applies to large and medium-sized enterprises as of December 30, 2026, and to micro and small enterprises as of June 30, 2027. These deadlines have remained unchanged under the Delegated Regulation.
Whether a used product falls under the EUDR again depends on what has happened to it in the meantime. If it is merely stored, cleaned, inspected, or sorted, it remains a used product. The EUDR requirements only apply if new relevant materials are added during repair or reconditioning, such as new wood or fresh natural rubber. Even then, the requirements apply only to the newly added components, not to the entire product.
Case study 1: Used tires
Why are tires generally subject to the EUDR?
Natural rubber is an important component of tires and, according to Annex I of the EUDR, is classified as a relevant raw material. According to estimates by the International Rubber Study Group, approximately 15 million metric tons are produced worldwide each year, with the majority of that in Asia. Europe accounts for a significant share of this: According to one study, vehicles registered in the EU consumed about five percent of global production in 2017, primarily for car tires. Because forests were specifically cleared to make way for many plantations, new tires fall under the EUDR as soon as they are first placed on the market in the EU. Used tires, on the other hand, are exempt, as are retreaded tires to a large extent.
Anyone importing new tires into the EU must prove that the natural rubber they contain was produced legally and without contributing to deforestation. The requirements for providing proof are substantial. It is not enough to know the country of origin. Traceability down to the individual cultivation site, verified by geographic coordinates, is required.
Does the EUDR apply to used tires?
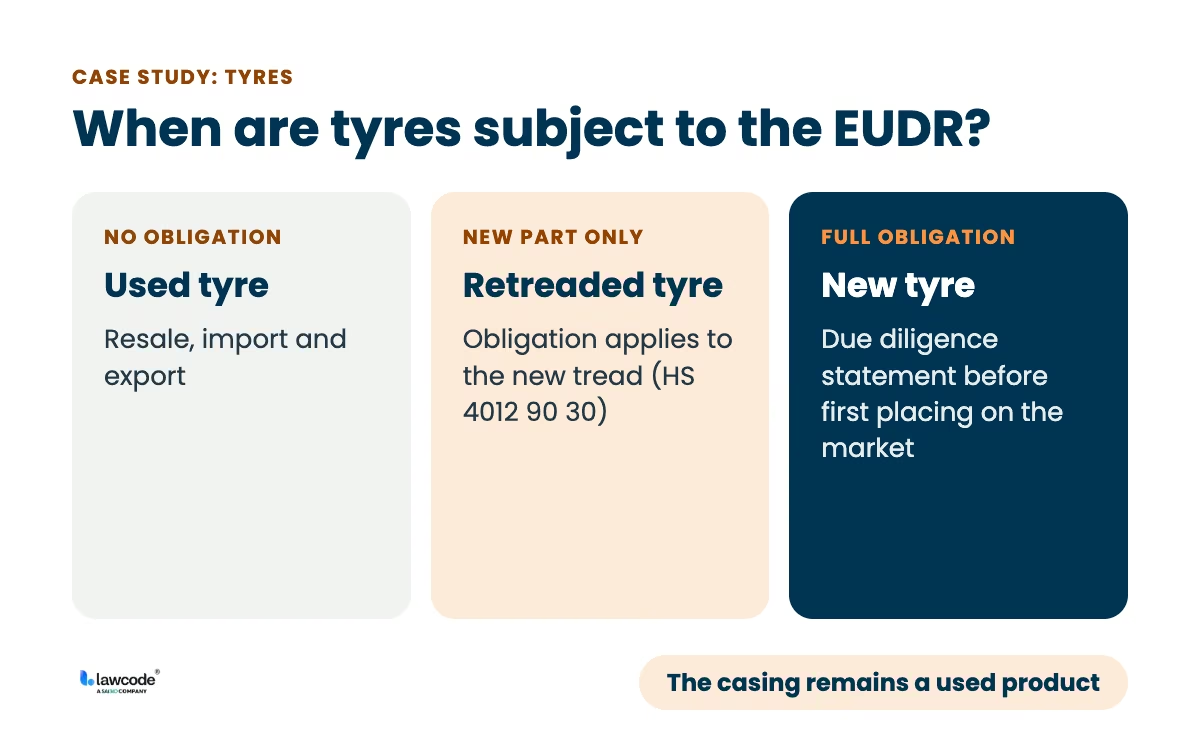
Used tires are exempt from the EUDR. Anyone who resells them within the EU is not placing them back on the market, provided they were already legally on the EU market. Since the Delegated Regulation (EU) 2026/2102 took effect, this exemption also applies to imports from third countries. For retreaded tires, the EUDR now covers only the new tread (HS Code 4012 90 30). This eliminates the previously required case-by-case assessment of whether retreading makes the entire tire a new product.
A typical example: A truck fleet replaces its tires after three years and sells the old tires to a used goods dealer. From the EUDR’s perspective, this is not a problem. The tires were already on the market, and as used goods, they are exempt from the regulation. This also applies if they are sold to another EU country, transferred between companies, or exported from the EU. Only when new relevant material is added—such as a new tread—do obligations arise again, and then only for that new component.
Does the EUDR apply to retreaded tires?
For retreaded tires, the EUDR applies only to the new tread. During the retreading process, the worn-out carcass is reconditioned, vulcanized, and fitted with a new tread layer. The carcass is a used product and is not covered by the regulation. The new tread, on the other hand, contains fresh natural rubber and is subject to the EUDR (HS Code 4012 90 30). The duty of care and the declaration of due diligence therefore apply only to this component.
Practical example: The fictional company Kessler GmbH, which specializes in tire retreading, processes several thousand truck tire casings annually. It purchases the tread compound from a manufacturer in the EU that has already submitted a due diligence statement for the natural rubber. Kessler GmbH therefore only records the reference number of this declaration for each batch. If, on the other hand, it imports the compound itself from a third country, it is considered a market participant and must issue the due diligence declaration.
What does EUDR compliance look like in practice?
Instead of wading through regulatory texts, we’ll show you live in 30 minutes how to collect geographic data, assess risks, and create due diligence statements tailored to your supply chain.
Case Study 2: Used Pallets
Are new pallets subject to the EUDR?
New pallets are subject to the EUDR if they are placed on the market as a standalone product. If they are used solely as packaging for other goods, they are not covered by the regulation.
Wood is one of the key raw materials covered by the EUDR and is a particular focus of attention as a potential driver of global deforestation. Shipping pallets, especially Euro pallets, are manufactured, exchanged, and reused by the millions in Europe. Most are produced in Europe. However, some also come from Asia or South America, usually as single-use pallets accompanying shipments of goods.
Under the EUDR, the key factor is the role in which a pallet is placed on the market. A manufacturer who sells empty pallets to logistics companies is placing a wood product on the market. The manufacturer must demonstrate the legal and deforestation-free origin of the wood before the pallets are placed on the market. The same applies to importers of empty pallets. Loaded pallets are expressly exempt from the EUDR because they are considered packaging. Delegated Regulation (EU) 2026/2102 specifically mentions pallets in pallet exchange systems.
Pallets that carry, support, or protect goods are considered packaging and are exempt. For reusable packaging, the exemption applies from the time it is actually used as packaging. A new pallet sold empty as a standalone product therefore remains subject to the EUDR, even if it later circulates in an exchange system.
Note: Pallets fall under HS Code 4415. A simple question can help with classification: Is the pallet itself being sold, or is it carrying something? If new, empty pallets are sold, imported, or exported as merchandise, the EUDR applies. If the pallet carries a shipment, it is considered packaging and is not covered by the EUDR.
Does the EUDR apply to used pallets?
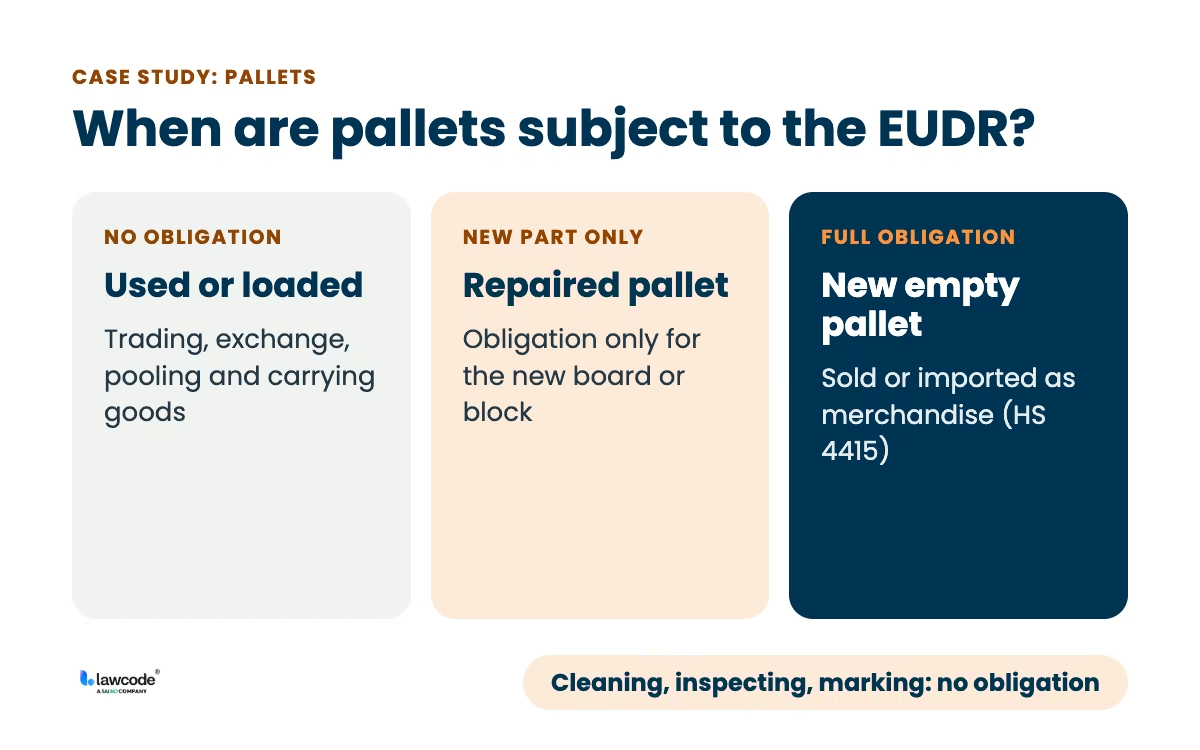
Used pallets are not subject to the EUDR as long as no new wood is incorporated into them. Since the Delegated Regulation (EU) 2026/2102, entry 4415 in Annex I has explicitly included the provision that used and secondhand products are exempt. If a pallet is traded, rented, exchanged, or transferred to another EU member state, no new due diligence obligation arises. This applies primarily to the open Euro pallet pool and closed pool systems, in which pallets remain in circulation for years.
Even cleaning, inspecting, marking, or pooling does not change this; the pallet remains a used pallet. The situation is different if wooden parts are replaced, such as a board or a block. In that case, the EUDR obligations apply to the new wood, not to the entire pallet. Who is responsible for these obligations depends on where the wood comes from. If a repair shop purchases the boards from an EU supplier, that supplier has already issued the declaration of due diligence. If the shop imports the wood itself, it is responsible for complying with these obligations.
Does the EUDR apply to pallets made from recycled wood or compressed wood? Pallets made exclusively from waste wood or used wood are not subject to the EUDR because waste, as defined by the Waste Framework Directive, is exempt, as are used components. However, manufacturers should be able to document the proportion of recycled material. If virgin wood is added, the requirements apply to that portion.
When do pallets become subject to the EUDR?
Pallets become subject to the EUDR as soon as new wood is added. This applies to repairs as well as upcycling.
In the case of repairs, the obligation applies only to new parts, such as a replaced deck board or support board. Cleaning, sorting, or marking, on the other hand, do not trigger any obligations.
When it comes to upcycling, two questions need to be addressed. First: Does the new product even fall under an item listed in Annex I? If not, the EUDR does not apply. Second: Does it contain new wood? If a product is made exclusively from used pallet boards, these are exempt as used components. If new wood is added, the requirements apply to that portion.
For commercial upcycling providers, this means, above all, that they should be able to document that their materials are actually used and should only use new wood with a traceable origin.
When are used goods subject to the EUDR?
Used pallet, resold as-is or exchanged
- Subject to EUDR: no
- Affected: none
- Responsible: nobody
Used pallet with a new board or block
- Subject to EUDR: Yes, only for new wood
- Affected part: the replaced component
- Responsible party: the timber supplier from the EU, or the repair shop if it imports the timber itself
New empty pallet as a commodity
- Subject to EUDR: yes
- Affected portion: the entire range
- Responsible Party: Manufacturer or Importer
Loaded pallet (new or used)
- Subject to EUDR: No, it is considered packaging
- Affected: none
- Responsible: nobody
Used tire, not reconditioned
- Subject to EUDR: No, even for imports and exports
- Affected: none
- Responsible: nobody
Retreaded tire
- Subject to EUDR: yes, only for the new tread (HS 4012 90 30)
- Affected part: the tread, not the carcass
- Responsible party: The supplier of the tread compound from the EU, or the retreader if it imports the compound itself
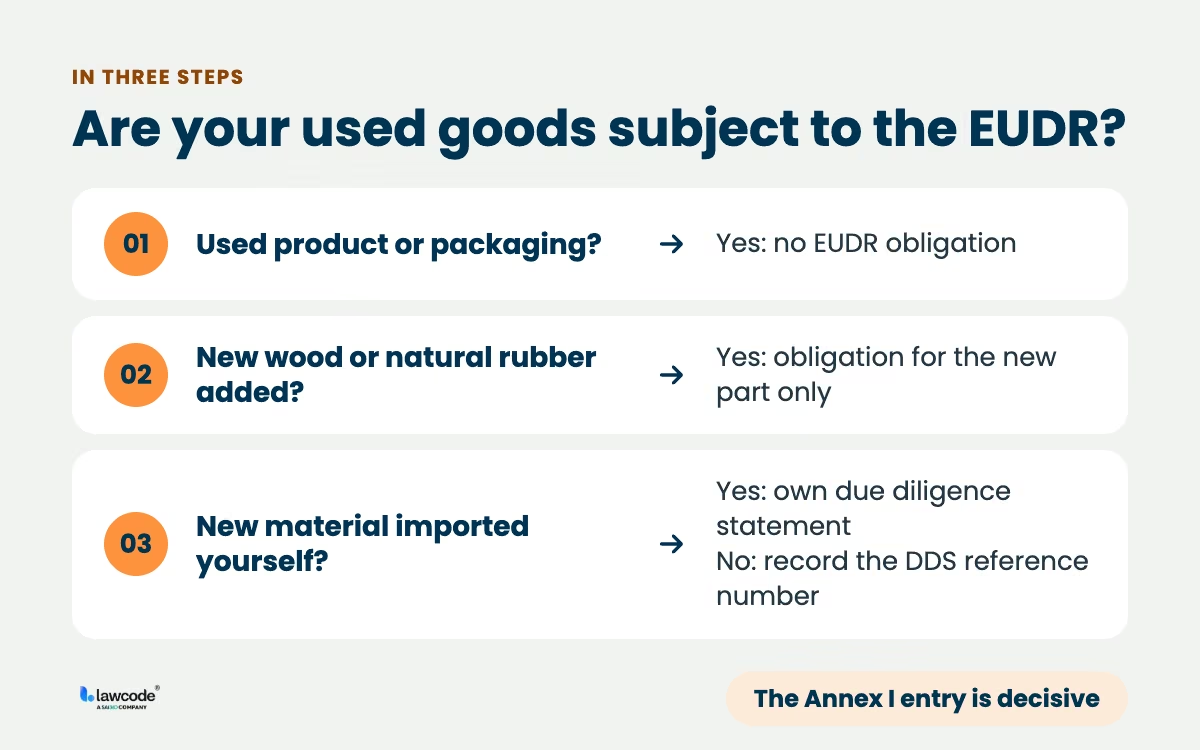
For used goods, the question can be answered by following three steps.
Decision logic for practice
Used and secondhand products are exempt from most wood, furniture, and rubber items listed in Annex I, whether they are resold within the EU or imported or exported. Pallets and other packaging that merely carry or protect goods are also exempt once they are used as packaging. The situation is different when new pallets are sold as a separate commodity.
When performing repairs, retreading, or upcycling, you must check whether new wood or new natural rubber has been incorporated. If so, the requirements apply only to this new material. Cleaning, inspecting, sorting, or marking are not included.
If the new material comes from a supplier in the EU, that supplier has already submitted the due diligence statement. The buyer records the reference number. If the material is imported directly from a third country, the importer is considered a market participant and must submit the due diligence statement themselves.
What should companies do now?
Companies that deal in or recondition used goods should have three matters clarified by the effective date of December 30, 2026: proof of used status, labeling on documents and in systems, and responsibility for newly installed materials.
How do you prove that an item is used?
Anyone who deals in used goods must, if in doubt, be able to prove that the goods are in fact used. This applies equally to large, medium, and small businesses. Documentation of the original purchase, delivery receipts, serial numbers, and details regarding previous use and maintenance are helpful in this regard.
If new material is added, such as a new tread or a new pallet board, the reference number of the due diligence statement must also be recorded; for simplified statements, the identification number must be recorded. This obligation applies to the first downstream operator who takes delivery of the goods from the upstream stage, not to every operator in the chain.
The easiest way to do this is with a central registry where all product information is stored. This helps prevent gaps in documentation even years later and ensures that inquiries from regulatory authorities can be answered quickly.
To Do:
Keep a central record of your used goods. Note when and where you purchased the items and how they were used. For new components, also note the DDS reference number. Keep all records for at least five years.
How do you label new and used goods in the supply chain?
Let suppliers and customers know early on whether the goods are new or used. The easiest way to do this is through invoices, delivery slips, or product descriptions. For transactions subject to the EUDR, the DDS reference and verification numbers must also be included on the accompanying documents and in the ERP system, preferably on a per-batch or per-delivery basis. Unique identifiers, such as barcodes, labels, or entries in the inventory management system, are also helpful.
To Do
Clearly indicate on invoices, delivery slips, and in your systems whether the goods are new or used. For shipments subject to the EUDR, be sure to include the DDS reference number for each shipment.
What are the guidelines for repairs, retreading, and upcycling?
Companies that retread, repair, upcycle, or perform routine maintenance on goods should keep detailed records of which new EUDR-relevant materials they install, such as new wooden components or a new tread made of natural rubber. The obligations apply only to these parts. It must also be clarified who issues the due diligence statement for the new material and whether a modified product falls under an entry in Annex I. In case of uncertainty, it is advisable to seek expert or legal advice in a timely manner. In Germany, the Federal Office for Agriculture and Food (BLE) can also be contacted as the competent authority.
To Do
When performing repairs, retreading, or upcycling, keep a record of which new EUDR-relevant materials you are installing. If in doubt, seek advice early on from an attorney or the relevant authority.
How do I find the right EUDR tool?
Conclusion
Used tires and pallets are not subject to the EUDR, whether they are resold within the EU or imported or exported. This was clarified by Delegated Regulation (EU) 2026/2102, which has been in effect since September 18, 2026. Obligations arise only when new EUDR-relevant material is added, and then only for that new portion. Whether the exemption applies to a particular product is determined by the relevant entry in Annex I.
The real challenge lies in practice: In case of doubt, companies must be able to demonstrate that a product is actually needed and where new materials come from.
Five questions to help you determine whether your company is prepared:
- Can you provide proof of when and where you purchased your used items?
- Do you clearly label new and used merchandise on invoices, delivery slips, and in your systems?
- When it comes to repairs and retreading, do you know what new material is being used and where it comes from?
- Are the DDS reference numbers for new components linked to the respective transactions?
- Do you keep all supporting documents for at least five years and can you quickly locate them if a government agency requests them?
If any of these questions remain unanswered, it is not a legal issue but rather a documentation issue. There is very little time left before the system goes live on December 30, 2026; micro and small businesses have until June 30, 2027.
Frequently asked questions
Obligations arise as soon as new EUDR-relevant material is added, such as new wood in pallets or fresh natural rubber in tires. They then apply only to this new material, not to the entire product. If a product is converted into a different product type, it must also be checked to see if it falls under an entry in Annex I. Cleaning or maintenance that does not involve new material does not trigger any obligations.
No, a minor repair that does not involve new raw materials does not change anything. The tire remains a used product and is exempt from the EUDR. Even in the case of retreading, the regulation does not apply to the entire tire, but only to the new tread (HS Code ex 4012 90 30).
No, used goods can be exported without an EUDR assessment. They are exempt from the regulation, so a due diligence statement or reference number for customs is not required. The only exception is if new, relevant material has been incorporated. In that case, the standard EUDR obligations apply to that portion.
Careful documentation of previous use, precise classification of used products and transparent communication along the supply chain can largely prevent unwanted compliance risks.
No, it doesn't depend on the quantity. Used parts are excluded, even if a large amount of new material is added. The EUDR requirements apply only to the newly added material, regardless of how large its proportion is.
Karim Boukaouche
LinkedInESG compliance expert - lawcode GmbH
Karim Boukaouche advises companies on the implementation of the EU Deforestation Regulation (EUDR) and supports the implementation of digital solutions for legally compliant supply chains. His specialist articles on the lawcode blog combine regulatory depth with practical recommendations for action.