 DE

Important facts
- Which rubber products are affected by the EUDR?
- All products under HS code 4001 with natural rubber content are affected; purely synthetic rubber (HS code 4002) is not covered.
- What is the difference between natural and synthetic rubber?
- The decisive factors are the origin, chemical composition and the relevant HS code. Natural rubber comes from plant sources, synthetic rubber is produced petrochemically.
- Is there a de minimis limit for natural rubber in the product?
- No, the EUDR has no fixed thresholds; even small quantities of natural rubber can be relevant if they determine the essential character of the product.
- How can companies classify rubber correctly?
- TARIC, the EZT online system and internal product data such as technical data sheets and supplier information should be used for correct classification.
- Why is the customs tariff number so important?
- Only products under HS code 4001 are subject to EUDR. Incorrect classification can result in fines or delays in customs clearance.
- What should companies do now?
- Check your entire product portfolio for rubber components, determine the applicable HS codes and introduce clear processes for verification.
Executive Summary
Natural rubber is now subject to the EU Regulation on Deforestation-Free Supply Chains (EUDR). This means that companies throughout the entire rubber supply chain must fulfill extensive due diligence obligations. The most important step in this process is the correct EUDR classification based on the customs tariff. The rule is simple: Only products made of natural rubber (HS Code 4001) fall under the EUDR. Synthetic rubber (HS Code 4002) is exempt.
What does this mean for companies? Even small amounts of natural rubber may be subject to reporting requirements—if they define the nature of the product. That’s why two steps are important: carefully check the material composition and correctly classify the product in the customs tariff. It gets particularly tricky with composite products. In these cases, it must be determined which ingredient predominates.
Who is affected? Not only importers of raw materials, but also manufacturers and distributors of semi-finished and finished products, particularly in the tire, medical, and construction industries. Companies should act now: use appropriate tools such as TARIC or EZT-Online, establish internal processes for tariff classification and record-keeping, and collaborate with customs authorities or specialized consultants at an early stage. Correct classification is the foundation for legally compliant implementation of the EUDR. It avoids compliance risks, makes supply chains transparent, and secures long-term access to the EU market.
Never miss an update on the EUDR again.
New specialist articles, regulatory updates and practical tips, straight to your inbox. Once a week, no spam.
New raw material registration: natural rubber under the EUDR regulation
Background: Extension of the EUDR commodity list
The EUDR is part of the European Union’s Green Deal and marks a paradigm shift for companies operating along global supply chains. Its core requirement: In the future, only deforestation-free raw materials and goods, as well as products and their derivatives, may be imported into the EU or placed on the market within the Union. The aim is to curb forest degradation and deforestation.
Palm oil, soy, wood, coffee, cocoa, and bovine derivatives were already on the list of regulated raw materials. In early 2023, a seventh raw material was added: natural rubber was officially included in Annex I of the EUDR.
The reason for this: Studies by environmental organizations show that the global cultivation of Hevea trees contributes significantly to deforestation in Southeast Asia and parts of Africa. The EU is responding to these findings with the expansion.
You can find all the basic information on the European Deforestation Regulation here.
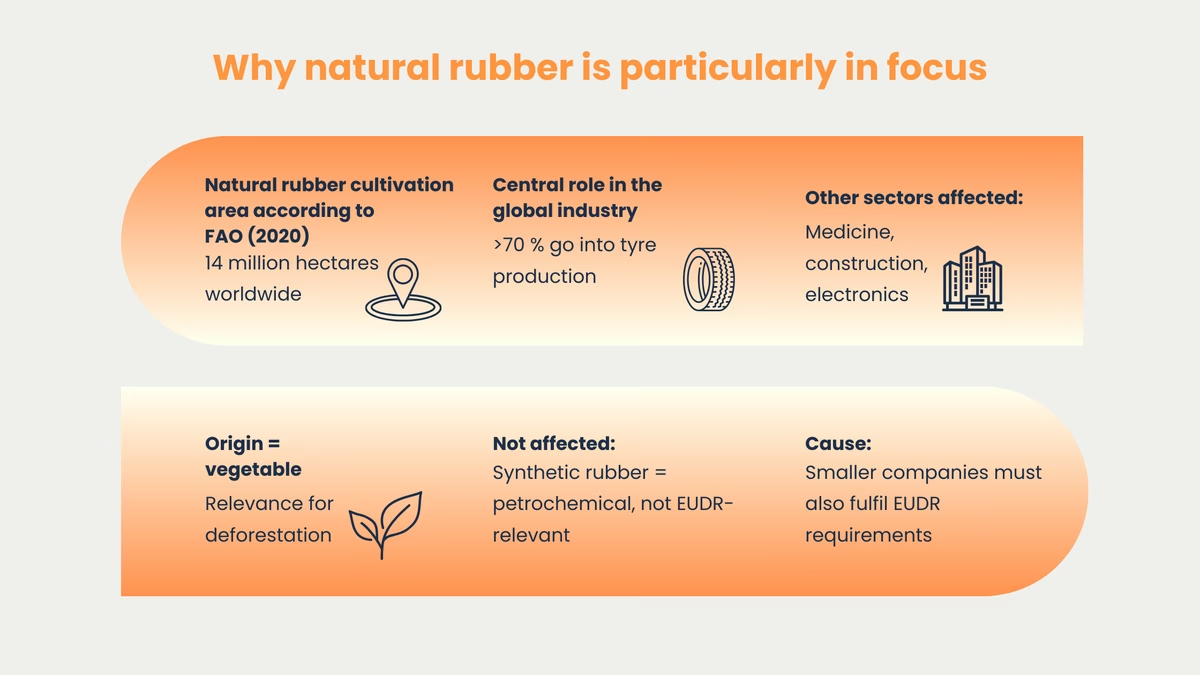
According to FAO statistics (2020), more than 14 million hectares of land worldwide were used for natural rubber production. This has consequences for biodiversity, local communities, and the global climate. The inclusion of natural rubber in the EUDR is therefore an important step toward more sustainable and transparent supply chains.
Why natural rubber is particularly relevant
Natural rubber plays an important role in global supply chains. Over 70% of global production is used for the manufacture of vehicle tires. But many other sectors, such as the medical, construction and electronics industries, also use rubber made from Hevea latex for their products.
Synthetic rubber is usually produced from petrochemicals and is not currently covered by the EUDR. The situation is different for natural rubber: Because of its plant-based origin and the potential deforestation effects associated with its production, it is a particular focus of legislation and is therefore covered by the EUDR classification.
Global trade in this raw material is massive. That is why even small processing companies and importers will have to invest in compliance efforts in the future.
Significance for companies
Who is affected: from raw material importers to processors
The EUDR applies to all companies that import natural rubber or products made from it into the EU for the first time or place them on the market there.
Many are affected: multinational tire manufacturers as well as specialized companies that produce, for example, medical technology, shoe soles, or conveyor belts. This also includes importers of semi-finished goods, suppliers to the automotive industry, and distributors of consumer goods.
Important to know: It’s not just entry into the EU market that matters. Any processing, blending, or customs clearance of the goods is also relevant.
Many products contain a blend of natural and synthetic rubber. For each individual product item, companies must therefore determine: What is the origin of the rubber it contains, and what is its percentage? This entails a significant amount of work in terms of product documentation, due diligence declarations, geolocation, supply chain traceability, and communication with suppliers from third countries.
Relevance of correct classification for compliance and customs
Whether a product is classified as natural rubber, a compound, or synthetic rubber has far-reaching legal implications. The correct HS codes (Harmonized System for customs tariff classification) must be used during customs clearance. The rule is clear: Only goods made of natural rubber—that is, all products under HS Code 4001—will be subject to EUDR requirements in the future.
Incorrect or inaccurate declarations can not only lead to delays in import and customs clearance, but in extreme cases can also result in fines, confiscations or reputational damage as a result of breaches of the EUDR. It should also not be underestimated that customs and compliance departments must work closely together in order to ensure seamless verification under the EUDR. The initial implementation in particular requires clear processes and decision-making guidelines for classification.
Planned adjustments by the Delegated Act 2026
The European Commission adopted the delegated act on July 13, 2026. Before it can take effect, it must still be approved by the European Parliament and the Council. It provides two key clarifications regarding the classification of rubber: Products made of vulcanized rubber, as well as conveyor belts and drive belts, are excluded from the scope of the EUDR. In addition, the definition of the type is clarified: only products made from Hevea brasiliensis count as natural rubber within the meaning of the regulation.
- "ex" marking for rubber codes: It is made clear that only products that are actually made from natural rubber are covered. This gives the character logic described in the article an explicit legal basis.
- Other species not covered: For rubber, products from plant species other than Hevea brasiliensis are not covered by the EUDR. The Hevea link is thus legally anchored.
- Retreaded tires (ex 4012 90 30 instead of ex 4012): The EUDR obligations are limited to the new rubber tread; the used tire carcass casing is no longer covered by the regulation. Background: Promotion of the circular economy.
Companies should prepare HS Code mappings and supplier communications accordingly, but mark them as "expected" until they are formally adopted.
Make EUDR Compliance a Breeze
Our EUDR module handles geodata collection, risk analysis, and due diligence reporting all in one place: automated, audit-proof, and without endless Excel spreadsheets.
Natural rubber vs. synthetic rubber
Origin and production in comparison
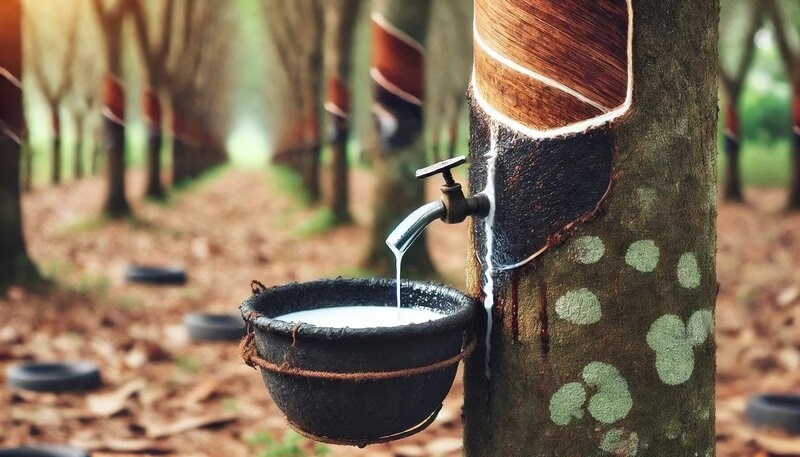
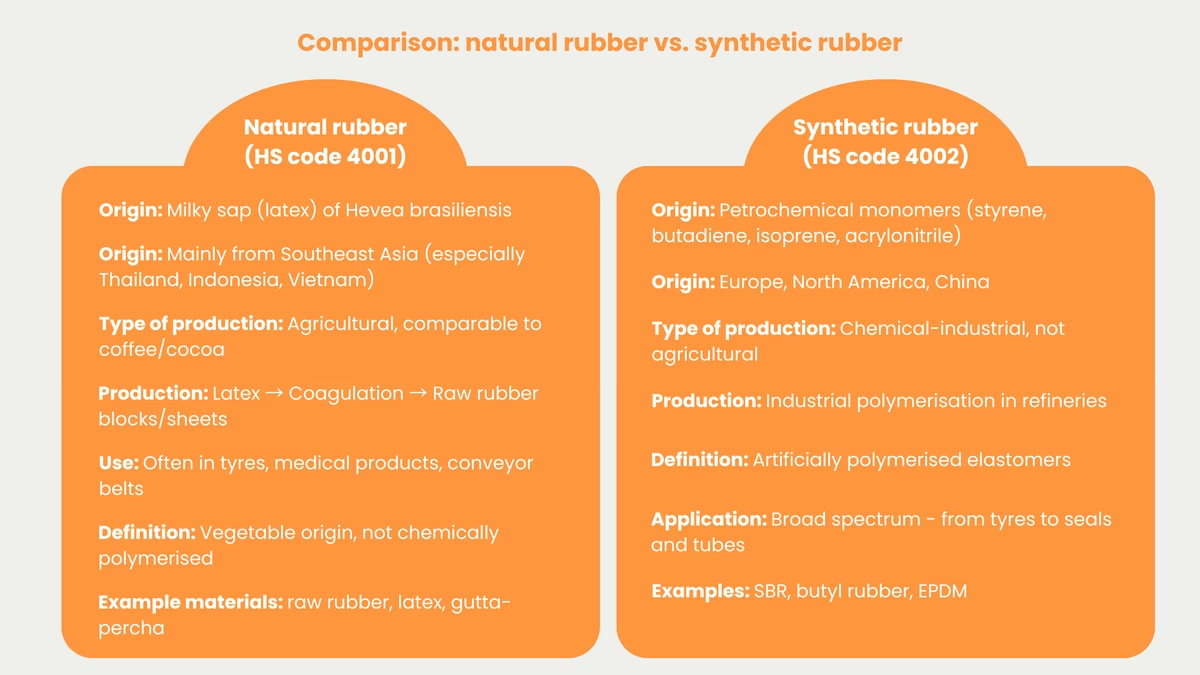
Over 90% of natural rubber is obtained from the latex of the Hevea brasiliensis tree. The main cultivation areas are in South East Asia, with countries such as Thailand, Indonesia and Vietnam dominating with around 70% of global production. After scoring the bark, the latex is collected, concentrated by coagulation and then processed into so-called raw rubber blocks or sheets. The extraction of this rubber is a classic agricultural primary production, roughly comparable to coffee or cocoa. This hevea bond is not only biologically practical, but also legally anchored: the draft Delegated Act 2026 makes it clear that rubber products from other species do not fall within the EUDR scope.
Synthetic rubber, on the other hand, is an industrially manufactured polymer product. Petrochemical monomers such as styrene, butadiene, isoprene, and acrylonitrile serve as raw materials. They are polymerized in refineries, primarily in Europe, North America, and China.
Well-known types include, for example, styrene-butadiene rubber (SBR), butyl rubber, and ethylene-propylene rubber (EPDM). The most important difference from natural rubber is that its production does not depend on agricultural land, but rather on industrial value creation and chemical processes.
Natural rubber vs. synthetic rubber:
Origin: plant-based (Hevea brasiliensis) vs. petrochemical (monomers such as styrene, butadiene)
Production: agricultural primary production vs. industrial polymerization
Main regions: Southeast Asia (Thailand, Indonesia, Vietnam) vs. Europe, North America, China
EUDR relevance: covered (HS 4001) vs. not covered (HS 4002)
Definitions in the context of customs law
Under customs law, a strict distinction must be made between natural and synthetic rubber.
In accordance with the EU customs tariff and relevant EU regulations, the following applies:
- Natural rubber is raw rubber produced by the coagulation of Hevea latex or the sap of related plants, whether in solid or liquid form. Importantly, the delegated act clarifies that only products derived from Hevea brasiliensis fall within the scope of the rubber definition. Other plant species are excluded. In doing so, the EUDR legally codifies a definition of origin that is already in practice.
- Synthetic rubber, on the other hand, includes all artificially polymerized elastomers whose main components are explicitly subsumed nationally and internationally under customs tariff number 4002.
Two factors are key for classification and EUDR categorization: the manufacturing process and the chemical composition. For composite products, such as modern automobile tires, a clear rule applies: they are classified according to their main component, provided that this component determines the nature of the goods. The legal basis for this is the General Rules for the Interpretation of the Combined Nomenclature (CN General Rules) of the European Union.
Relevant HS codes according to customs tariff
Two HS codes are central to classification in the customs tariff and the EUDR rubber classification:
- HS code 4001: this includes only natural rubber, balata, gutta-percha, guayule, chicle and similar natural rubbers, both raw and pre-processed. This also includes frozen, smoked or dried rubber.
- HS code 4002: this includes synthetic rubber, including "chemically modified" products. This applies to all petrochemically produced types of rubber.
Compliance with these HS codes is particularly critical as part of the EUDR check and in international goods traffic: only goods under 4001 are relevant for the EUDR, while items declared under 4002 remain exempt. This has consequences for both the customs declaration and the subsequent compliance check. Companies should check existing goods databases, article master data and supplier declarations to ensure that they are correct and up to date for customs tariff classification.
Clarification by the draft delegated act 2026: Several previously blanket-listed HS codes for rubber and oil palm products will be given the prefix "ex". This legal clarification makes it clear that only products that are actually made from the relevant raw material - i.e. natural rubber - are covered. The legislator is thus formally establishing what already applies in practice: a product is only covered by the EUDR if its natural rubber content determines the character of the product. Mixed products with predominantly synthetic rubber remain outside the scope even if they are formally classified under a rubber-related item. Note: As of May 2026, the amendment has not yet been published in the Official Journal - HS code mappings should therefore be marked as "expected".
Which types of rubber are affected by the EUDR?
Natural rubber within the scope of the EUDR
Natural rubber is explicitly listed in Annex I of the Regulation and is therefore subject to the requirements of the EUDR. This means that comprehensive due diligence requirements must be met for all products under HS Code 4001, as well as for products manufactured from them that contain rubber as their main component. These include complete data on the supply chain, growing region, and harvest year; satellite-based evidence confirming that no deforestation occurred; and information on producers and intermediaries.
Specifically, this means that anyone importing natural rubber—for example, as a raw material or latex milk—must have all the necessary documentation for EUDR compliance ready before the import takes place. Upon request, this documentation must be presented to the authorities, usually customs.
"Downstream" companies may also be affected—such as tire manufacturers or textile companies—specifically when their raw materials or intermediate products contain a significant amount of natural rubber.
If rubber is synthetic, it's left out—why?
Unlike natural rubber derived from plants, synthetic rubber is derived entirely from petrochemicals. The EUDR therefore classifies it as “not relevant to deforestation”; its production requires no agricultural land and no clearing of forest areas.
As a result, there are currently no specific EUDR requirements regarding traceability or proof of sustainability for the import and placing on the market of synthetic rubber, whether as a raw material, semi-finished product, or finished product.
While this regulatory loophole does sometimes lead to shifts in competition in practice, it is consistent with the EUDR’s objective: to reduce imported deforestation at the EU level. Even blended products containing a predominant proportion of synthetic rubber (and bearing the corresponding HS code) are currently not subject to reporting requirements.
Typical practical examples for classification
In practice, there are many challenges. For simple products such as household gloves, the classification can usually be made directly via the material code: If the gloves are made of 100% natural latex, they fall under the EUDR. However, if they are made of synthetic nitrile rubber, they are not affected.
Another example is car tires, which usually contain material mixtures of natural and synthetic rubber. Here, it must be precisely determined which component determines the character of the end product.
Special case of retreaded tires: The draft delegated act of May 2026 provides for the previously blanket HS code ex 4012 to be replaced by the more precise code ex 4012 90 30. Consequence: In future, the EUDR obligations for retreaded tires will be limited exclusively to the new rubber tread. The carcass casing as a used tire at the end of its life cycle is no longer covered by the regulation. This clarification is intended to promote a circular economy and significantly reduces the burden on manufacturers and importers of retreads, as they will only have to comply with due diligence obligations for the newly applied natural rubber content. Important: As of May 2026, the amendment has not yet been published in the Official Journal and is therefore not yet formally binding; HS Code mappings should be marked accordingly as "expected".
Companies are obliged to document which rubber has been processed and in what proportions by means of material analyses, supplier information and technical specifications
In the construction and industrial sectors, this question arises primarily in connection with sealing rings, vibration dampers, profiles, and elastic mountings. In technically demanding applications, synthetic rubber such as EPDM or butyl rubber is usually the material of choice. The reason: it offers greater resistance to weathering, UV radiation, and chemicals. Natural rubber, on the other hand, is more commonly found in components subject to mechanical stress, such as vehicle mountings or vibration dampers. Since many of these components are installed in systems, vehicles, and machines, correct classification is also important for downstream manufacturers.
Conveyor belts in industry often consist of mixtures, whereby the base layer can also be decisive. Mixed products with a clear synthetic overweight are usually listed under 4002 despite natural components and are not EUDR-relevant. The situation becomes more complex for articles with a multi-layer structure or a low natural rubber content. Here, the material characterization and the common classification logic according to customs regulations and EUDR often count.
The issue of classification also arises regularly in medical technology. Surgical gloves, catheters, ventilator tubing, and IV lines are made partly of natural latex and partly of synthetic materials such as silicone, polyisoprene, or nitrile rubber. Due to latex allergies, many manufacturers deliberately opt for synthetic alternatives. This has a practical side effect: under the EUDR, these products fall outside the scope of the regulation. For latex products, on the other hand, due diligence requirements apply in full, including the obligation to trace the origin all the way back to the plantation.
In the footwear industry, soles are a typical example of mixed materials. Outdoor and safety shoes often contain natural rubber because of its superior slip resistance. Sports shoes, on the other hand, are often made from synthetic materials. The same rule applies here: what matters is which component defines the nature of the sole. If the outsole is predominantly made of natural rubber, the final product falls under the EUDR, even if other parts of the shoe are made of synthetic materials.
Check EUDR relevance of rubber in products
Classification based on the customs tariff and the Combined Nomenclature
The classification of rubber under the EUDR begins with the precise classification of goods according to the customs tariff and the Combined Nomenclature (CN), which is the first and most important step in ensuring compliance. Companies must determine for each product whether its main component qualifies as natural or synthetic rubber. The General Rules for Classification in the Customs Tariff (General Rules 1 through 6) and the Explanatory Notes to the Harmonized System (HS) serve as guidance for this purpose.
The determination of the nature, origin, and chemical composition of the products should be based on existing product documentation and material data sheets. The result of the tariff classification is crucial: It determines not only the applicable HS code but also whether traceability and due diligence obligations under the EUDR apply. Companies can use digital tools for support: TARIC (the EU’s electronic customs system) and the German portal“EZT-Online”help verify the correct classification and fill in any missing information.
When products are considered EUDR-relevant
The decisive factor for EUDR relevance is whether a product or its components are considered natural rubber within the meaning of HS code 4001. It is not only the quantitative composition that matters, but also which component gives the product its technical and economic character. The draft delegated act 2026 enshrines this logic in law through the "ex" marking: only products that are actually made from natural rubber fall under the respective tariff heading. Products with a predominantly natural latex content, such as medical hoses or tires with a high natural rubber content, are subject to notification. By contrast, products with a predominantly synthetic content or chemically modified rubbers are not subject to the regulation.
Companies should also be aware that EUDR thresholds or de minimis limits do not automatically apply: Even small quantities of natural rubber in the end product can result in it falling under EUDR as long as the content determines the main character of the goods. In case of doubt, it is advisable to obtain binding customs information or consult with specialized customs advisors.
Practical steps for checking the classification
In practice, collaboration between the customs department, purchasing, and compliance is essential, especially in small and medium-sized businesses.
Here's the best way to proceed:
- First, take stock of relevant products: Which goods and product categories contain rubber or could be of natural origin? Then check the composition using material lists, supplier information, and data sheets. For composite products, document how the characteristic component is derived.
- The next step is to verify the data against the customs tariff, ideally digitally via TARIC or industry-specific tools. If in doubt, you should obtain a binding customs ruling or an expert opinion.
- For day-to-day operations, follow these guidelines: Centralize the tracking of compliance-related documents, such as supplier declarations and proofs of origin, so they are readily available for every import. Regular audits or spot checks help ensure EUDR compliance, even when product changes occur or new suppliers are introduced.
In these steps to EUDR-compliant rubber classification:
- Inventory - identify all products and product groups containing rubber
- Analyze composition - evaluate material lists, supplier information and technical data sheets
- Check customs tariff classification - determine HS code via TARIC or EZT-Online and compare with Annex I
- Clarify cases of doubt - obtain binding customs information or expert opinion in case of uncertainty
- Record documents centrally - archive supplier declarations and certificates of origin in an audit-proof manner
- Check regularly - update classifications in the event of product changes or new suppliers
Conclusion
The EUDR marks a turning point for the rubber industry: Correctly distinguishing between natural and synthetic rubber lays the foundation for EUDR compliance and legally compliant trade.
Companies should do three things: carefully review their product portfolio, assign all rubber-containing goods to the appropriate HS codes, and, in the case of composite products, identify which component is predominant.
Electronic tools, clear procurement processes, and close collaboration between purchasing, production, and compliance can help with this. Taking action early on can save you trouble, delivery issues, and financial risks down the road.
Frequently asked questions
The most important step: carefully review the material composition and determine which component gives the product its essential character. Also, use the electronic customs tariff (TARIC) and EZT-Online to ensure you select the correct HS code. And document all supplier information and production details.
If products, e.g. tires or finished goods, are declared under the wrong HS code, this can lead to rejection at the border, fines, subsequent customs clearance or reputational damage. A breach of EUDR obligations is particularly serious, as it can lead to severe fines and exclusion from the EU market.
In most cases, clear and verifiable material documentation—such as supplier information, technical data sheets, or manufacturer specifications—is sufficient. However, for particularly complex or new products, a laboratory analysis may be necessary to verify the rubber content that defines the material’s properties.
There are several solutions available for the practical implementation of EUDR classification: the EU’s electronic customs tariff (TARIC), the German tool EZT-Online, and specialized compliance management systems for supply chain traceability, such as our EUDR module.
The EUDR currently has no fixed threshold values. The decisive factor is whether the product is to be classified as a natural rubber product (HS code 4001) according to the customs tariff and goods description. Small quantities are relevant if they determine the character of the goods.
No, synthetic rubber is not covered by the EUDR. It is classified under HS Code 4002 and is of petrochemical origin. Since its production does not require agricultural land or the clearing of forest areas, the EUDR classifies it as “not relevant to deforestation.” This applies regardless of whether it is imported or placed on the market as a raw material, a semi-finished product, or a finished product.
Matthias Klein
LinkedInESG compliance expert - lawcode GmbH
Matthias Klein advises companies on the implementation of supply chain laws such as the CSDDD and supports the implementation of digital solutions for legally compliant supply chains. His specialist articles on the lawcode blog combine regulatory depth with practical recommendations for action.