 DE

Important facts
- How does a company's size under the EUDR affect its obligations?
- The EUDR makes a clear distinction between large companies and SMEs. This determines whether full or simplified due diligence obligations apply.
- How are SMEs defined under EU law?
- The Accounting Directive 2013/34/EU is decisive: a company is considered a medium-sized company if it does not exceed at least two of the three thresholds: € 25 million total assets, € 50 million net turnover, 250 employees. A change in size only occurs after two consecutive financial years.
- How does the group structure affect the threshold test?
- The EU Commission has expressly clarified this in the 5th FAQ iteration: The thresholds are to be examined per legal entity; consolidation at group level does not take place. Each subsidiary is assessed individually according to its own values (FAQ 3.10 and 3.13).
- Is a subsidiary considered an SME if it meets the thresholds itself?
- Yes, according to FAQ 3.13 of the EU Commission, the balance sheet total, net turnover and number of employees of the individual legal entity are decisive, not those of the group as a whole. A small subsidiary in a large group can therefore be classified as an SME.
- What exactly do SME retailers need to do to be EUDR-compliant?
- They must ensure that they can produce, pass on and archive a valid reference number of the due diligence declaration for each product.
- What does the reference number mean in practice?
- It is proof that a product has undergone EUDR-compliant due diligence and must be carried with every transaction.
- How can EUDR implementation be organized efficiently within the Group?
- Through a clear allocation of roles (market participant vs. trader), central threshold checks, compliance processes and digital systems for managing reference numbers.
Executive Summary
The EU Deforestation Regulation (EUDR) distinguishes between three types of actors with different due diligence obligations: operators (market participants), downstream operators, and traders. Operators must implement a comprehensive due diligence system that includes risk analysis and a due diligence statement, while simplified due diligence obligations apply to downstream operators and traders, particularly SMEs.
The classification of SMEs is based on the Accounting Directive 2013/34/EU (not on the SME Recommendation 2003/361/EC, FAQ 3.10). The key criterion is that at least two of the three thresholds must not be exceeded: €25 million in total assets, €50 million in net revenue, or 250 employees. A change in size takes effect only after two consecutive fiscal years.
SME dealers arenot requiredto conduct their own risk analyses; however, they must document the market participant’s due diligence statement, verify it using a reference number, and retain the records for at least five years. It is essential to clearly define roles within corporate groups and to use a system-based approach to managing reference numbers. An annual review of the classification is recommended.
Never miss an update on the EUDR again.
New specialist articles, regulatory updates and practical tips, straight to your inbox. Once a week, no spam.
EUDR: objectives, background and obligations
The EUDR (EU Deforestation Regulation) aims to curb deforestation and forest damage worldwide by ensuring that only deforestation-free products enter the EU. It applies to companies that import certain raw materials or products into the EU or sell them within the EU. The regulation distinguishes between different types of companies.
There are some exceptions or simplified rules for small and medium-sized enterprises (SMEs). The exact requirements that apply often depend on the size and structure of the company in question.
In day-to-day business, groups of companies in particular, such as parent companies, subsidiaries, holding companies or joint ventures, are often faced with the question of how to correctly determine and apply the thresholds and obligations of the EUDR. In addition, there is often uncertainty as to what role a company plays in the supply chain, whether as a market participant or as a trader, and how this affects implementation (e.g. due diligence obligations, documentation, risk assessment). Particularly in the case of complex corporate structures or small companies with a strong division of labor, it is important to identify the obligations precisely.
When do which EUDR obligations apply?
By December 30, 2026, companies in the EU must be able to demonstrate transparently that their products do not contribute to deforestation or forest degradation. The regulation particularly affects players that import relevant raw materials such as wood, coffee, cocoa, soy, palm oil, rubber and cattle products or are the first distributors in the EU. Products made from these raw materials are also important and must be taken into account. The EUDR makes a clear distinction as to whether a company acts as a market participant or trader and whether it is an SME as defined by the EU.
Operator, downstream operator and trader - the three roles of EUDR players
The EUDR differentiates between three functional roles.
The operator (market participant) places a relevant product on the EU market for the first time or exports it from the EU. Typical examples include importers or producers within the EU. Operators bear the primary responsibility: They must fulfill their full due diligence obligations and submit a due diligence statement (DDS).
The downstream operator processes relevant products already present in the EU into new relevant products and places them on the market or exports them. An example: a chocolate manufacturer that further processes imported cocoa. The operator is not required to conduct its own due diligence or submit a DDS; instead, it must simply fulfill certain information obligations: It must ensure traceability, retain the DDS reference numbers for five years, and report any suspected non-compliance.
The trader resells a relevant product that has already been placed on the market, for example in retail or wholesale. Downstream operators and traders share the same basic obligations under Art. 5 EUDR. Non-SMEs in these roles must also register in the information system and actively verify any substantiated concerns.
Operator, downstream operator and trader - the most important differences:
- Operator: first placing on the market or export - full due diligence incl. DDS, traceability and geodata
- Downstream operator: Processing of products already placed on the market into new relevant products - no own DDS, but record and pass on reference numbers
- Traders: resale of unchanged products - reduced obligations, SME traders benefit from additional simplifications
The "first downstream" logic - who has to record the reference number?
One of the most important clarifications in FAQ Iteration 5 concerns the question of which downstream market participant in the supply chain is actually required to include the DDS reference number. Answer: Only the first downstream operator (or trader) is required to do so, and even then only passively. They are not required to actively verify whether their supplier is an operator, nor are they required to actively request the reference number. The obligation to provide the reference number rests with the operator (Art. 4(7) EUDR).
Specifically, this means (FAQ 3.4 and 3.5): If a company does not receive a reference number from its supplier, it may assume that it is not first downstream in accordance with the "good faith" principle. Only if it is aware that its supplier is an operator and does not pass on the number may it not place the product on the market.
Practical implication for SME retailers: They must establish an inbound process that systematically records incoming reference numbers, assigns them to the corresponding product, and retains them for five years. A separate systematic review is not necessary, nor is it necessary to follow up with suppliers or maintain an in-house DDS.
Standard obligations and simplifications - the importance of company size
The standard obligations of the EUDR apply to all market participants, regardless of size. For traders, however, the decisive factor is whether or not the company qualifies as an SME as defined by the EU. The SME classification according to the Accounting Directive 2013/34/EU is decisive here (see below: €25 million balance sheet total, €50 million net turnover, 250 employees - not exceeding two out of three).
The EUDR provides significant relief for traders who are classified as SMEs, as they do not have to submit a separate due diligence declaration for each delivery. Under certain conditions, they may refer to the due diligence declarations of their upstream suppliers. Nevertheless, a number of documentation and cooperation obligations remain, e.g. to retain the due diligence declarations and in the event of inquiries from authorities.
From a practical point of view, it is therefore crucial whether a company exceeds or falls below the EUDR thresholds - in each case at the level of the individual legal entity, not the group of companies.
Special case: micro and small "primary operators"
In addition to the simplifications for SME traders, there has been a second simplification component since the targeted adjustment at the end of 2025 that is often overlooked. It is aimed at micro and small primary operators, i.e. actors who produce relevant raw materials or products themselves and place them on the market for the first time. This group is not required to submit a full due diligence declaration for each process. Instead, a one-off simplified declaration in the EU system is sufficient, from which a declaration identifier is then generated. This identifier then serves as a verification and traceability anchor for the products concerned. In certain cases, these primary operators may also provide a postal address if this clearly assigns the production to a location.
Important
For EUDR micro-enterprises, a special rule applies regarding MSPO status: This status requires the cumulative fulfillment of four conditions:
- a natural person or a micro- or small enterprise as defined in Accounting Directive 2013/34/EU,
- Headquartered in a country classified as low-risk,
- direct placement on the EU market or export,
- Products produced in-house in the country where the company is based.
The relevant SME definition: Accounting Directive 2013/34/EU
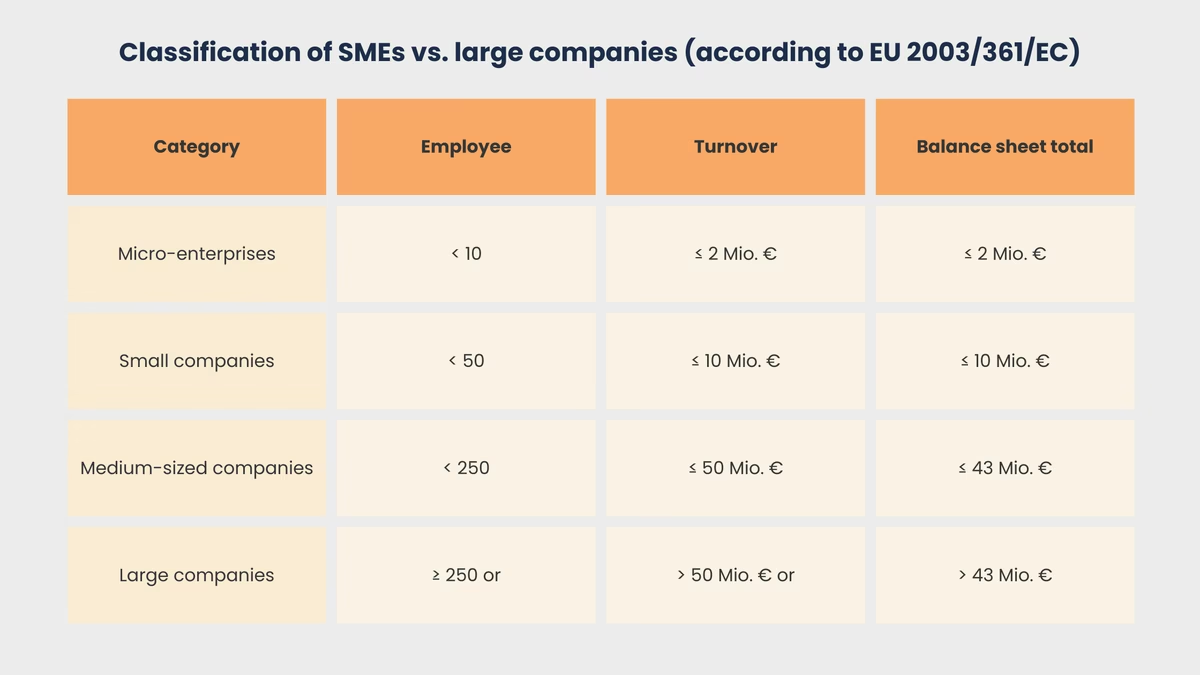
The EU Commission’s SME Recommendation 2003/361/EC is often mistakenly cited as the basis for the EUDR’s definition of an SME. This explicitly does not apply to the EUDR. FAQ 3.10 of the 5th iteration clarifies: The thresholds set forth in the Accounting Directive 2013/34/EU (as amended by Delegated Directive 2023/2775) are decisive. The thresholds for “small” and “medium-sized groups” set forth in Article 3(5) and (6) of the Accounting Directive are also not relevant for the EUDR.
A company is considered a medium-sized company if it does not exceed at least two of the following three values on the balance sheet date:
- Balance sheet total: € 25 million
- Net sales: € 50 million
- Average number of employees in the financial year: 250
Small enterprises fall below at least two of these three thresholds, while micro-enterprises fall significantly below them. In Germany, the national implementation under Section 267 of the German Commercial Code (HGB) applies to the definition of SMEs for EUDR-relevant thresholds. For small businesses, the criteria are as follows: total assets of no more than €7.5 million, revenue of no more than €15 million, and no more than 50 employees (at least two of the three criteria must not be exceeded).
Important: A change in size only occurs if the thresholds are exceeded or undercut in two consecutive financial years. A one-off "outlier year" does not change the classification.
For small and micro-enterprises subject to the EUDR, there is an important special rule regarding the effective date: Whether a company benefits from the later effective date of June 30, 2027 (instead of December 30, 2026) depends on whether it was established as a micro or small enterprise as of the cutoff date of December 31, 2024.
EUDR Group Structures: How Are Holdings Counted?
In practice, many companies are part of a corporate group, whether as a subsidiary, a holding company, or through indirect ownership interests in other companies.
The EUDR therefore raises the question: is each group company assessed individually or does the entire group count? The EU Commission has clearly answered this question in the 5th FAQ iteration and the answer deviates from the usual logic of many other EU regulations.
Basic principle: Individual consideration of the legal entities
In principle, individual legal entities are considered under European law. A company that has its own legal existence and entry in the commercial register is therefore treated as an independent entity. As a result, the EUDR obligations are triggered at the level of the respective legal entity. The EUDR therefore has an important special feature: unlike the SME Recommendation 2003/361/EC, which works with the concept of associated enterprises and partner enterprises, group membership is irrelevant for SME classification under the EUDR.
Individual consideration instead of consolidation - the EU Commission's clarification
Unlike many other EU regulations, the EUDR does not apply a consolidated threshold analysis at group level. FAQ 3.13 makes it very clear that the due diligence obligations apply to "persons" within the meaning of Art. 2(20) EUDR - regardless of whether they are part of a group of companies or not. Subsidiaries, like any other legal entity, must check whether they are to be classified as an SME based on their own balance sheet total, net turnover and number of employees. The decisive factor is the individual legal entity, not the group as a whole.
This has an important technical consequence: every group company that acts as an operator, non-SME downstream operator or non-SME trader must maintain its own account in the EU information system. The system expressly does not provide for group-wide omnibus accounts.
The following also applies within group supply chains: each legal entity is considered individually. In the case of several transactions within a group, the first downstream operator or trader may well be a sister company (FAQ 3.8).
Example to illustrate: A German parent company has 200 employees, € 60 million in sales and € 30 million in total assets - it is therefore not an SME. Its German subsidiary, which imports coffee, has 40 employees, a turnover of € 8 million and a balance sheet total of € 4 million. According to FAQ 3.13, the subsidiary is classified as a small company despite being part of a group. It therefore benefits from the later application on June 30, 2027 (if already established as small/small as of December 31, 2024) and from the simplifications for SME players.
Group-wide efficiency despite individual consideration: The authorized representative
Even if each group company needs its own account, the EUDR offers a central solution: According to Art. 6 EUDR, an authorized representative (with an EU branch and a written mandate in accordance with Art. 2(22)) can submit and jointly manage DDSs and SDs for several group companies. The legal responsibility remains with the respective group company, but the operational burden can be centralized - for example with a specially established compliance function at holding company level.
Scenario: Subsidiary of an international group
A German subsidiary of an international group independently imports coffee products. It employs 40 people, generates € 8 million in sales and has total assets of € 4 million. The French parent company has 180 employees, a turnover of € 60 million and a balance sheet total of € 30 million.
According to FAQ 3.13, the German subsidiary is considered in isolation. With 40 employees, a turnover of €8 million and a balance sheet total of €4 million, it remains well below the thresholds and is considered a small company - regardless of the fact that the parent company is a non-SME. The later application of the EUDR from June 30, 2027 therefore applies to it (prerequisite: status on December 31, 2024) and it benefits from the simplifications for SME players. However, as an operator, it is still required to register itself in the information system; alternatively, the parent company can appoint an authorized representative to submit the DDS centrally for several group companies.
See the EUDR solution in action
In just 30 minutes, we'll show you how your team can manage geographic data, risk analyses, and due diligence reports centrally and without any manual effort going forward.
Requirements for SME Retailers Along the Supply Chain
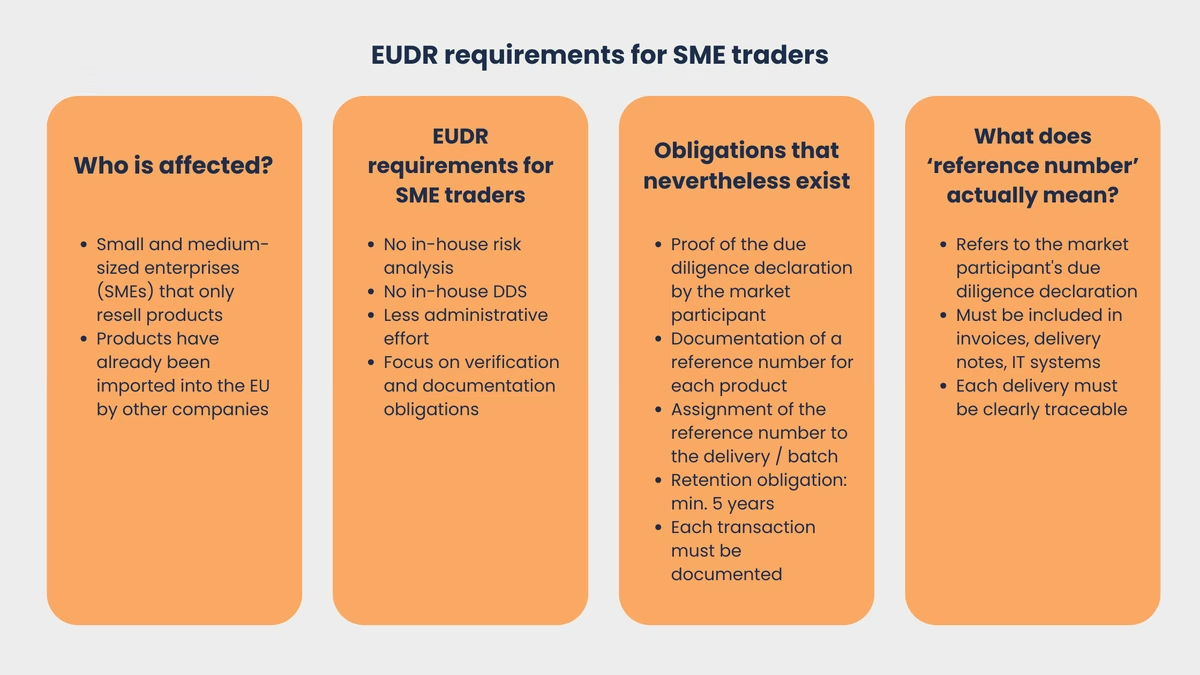
Many small businesses are not considered market participants under the EUDR but act solely as distributors. They sell products that other, typically larger companies have already imported into the European Union. Simplified rules apply to such SME distributors and SME downstream operators under Article 5 of the EUDR.
Facilitations for SME traders according to EUDR
The EUDR regulations provide several exemptions for SME traders and SME downstream operators: They are not required to submit their own Due Diligence Statement (DDS) or conduct their own risk analysis. They are also exempt from registration in the EU information system.This obligation applies only to non-SME downstream operators and non-SME traders (Art. 5(2) EUDR). Further due diligence obligations arise only in the event of “substantiated concerns,” and even then, they apply only to non-SMEs.
The European Commission justifies this simplification by stating that it is intended to reduce the administrative burden on smaller businesses. This significantly reduces the burden on SME merchants: They can focus on their core obligations instead of having to comply with the extensive documentation and analysis requirements imposed on market participants.
It is important to distinguish between two different mechanisms: The exemptions for SME retailers apply to retailers who resell products that have already been covered by an operator—that is, further down the supply chain. The simplification for micro and small primary operators, on the other hand, applies right at the beginning of the chain. Here, instead of a complete DDS for each transaction, a one-time simplified declaration and a Declaration Identifier are used.
Obligations that nevertheless exist
Even though SME retailers are exempt from many administrative obligations, they are not completely exempt from the EUDR. Two obligations remain key: Every retailer must verify and archive the market operator’s due diligence statement. And for every transaction, it must be ensured that a unique reference number for the respective due diligence statement is available and that it can be unambiguously assigned to the product or the respective batch.
In addition, SME retailers must retain the supporting documentation for at least five years so that it can be presented to the relevant authorities or used during audits, if necessary. This documentation requirement applies to all transactions involving affected products within the supply chain.
Reference number instead of full DDS - what does this mean in concrete terms?
The reference number is the central link in EUDR compliance for SME traders. It refers to the due diligence declaration issued by market participants and must be documented for each delivery. In practice, this means that the reference number for each delivery or batch must be clearly assignable internally, archived in an audit-proof manner and transferable if required. Many companies solve this by carrying the predominant reference in ERP and document processes without having to generate new proofs at each stage of the chain.
Companies can adapt their existing systems—such as ERP, inventory management, or compliance software—so that reference numbers are automatically recorded and stored. It is also important to note that every transaction requires the appropriate due diligence statement. Reference numbers must not be assigned twice or lost; otherwise, penalties may be imposed during an audit.
Recommendations for Action on Implementing the EUDR for Corporate Groups and SMEs
Clarification of the distribution of roles within corporate groups
Within corporate groups, it must be clear who is a market participant and who is a distributor: Who is the first to import into the EU, and who is the distributor? This role must be documented for each company in the group.
For affiliated companies, it is recommended to establish a central function (e.g., a compliance officer) to oversee the assignment of responsibilities and ensure consistency across the group. Where legally permissible, the duty of care may also be fulfilled centrally by the parent or holding company.
Uniform valuation within the Group
The SME classification and thresholds should be reviewed and documented annually, preferably in collaboration with the legal and compliance department, for example as part of the annual financial statements. If the company’s structure changes—for example, due to new investments or the establishment of new companies—this must be taken into account. This documentation is important because it serves as evidence in the event of an audit.
For SME dealers: Efficient system for managing reference numbers
SME retailers are advised to use existing systems, such as ERP or compliance software, to manage EUDR reference numbers—for example, the EUDR module, which automatically performs all key checks on a single platform.
The reference number should be designated as a required field in the processes for goods receipt, invoicing, and inventory management. There should also be clear guidelines on how the number is passed on and securely archived. Employees in retail, purchasing, and sales should understand why the number is important. This reduces the risk of complaints from regulatory authorities and ensures that all transactions are legally compliant.
To Do:
- For each company in the group, determine whether it acts as an operator, a downstream operator, or a trader, and document this role assignment in a transparent manner.
- Designate a central compliance function that coordinates EUDR obligations across the Group and ensures uniform interpretation.
- Review the SME classification annually and transparently incorporate changes in the company's structure—such as new equity investments—into the assessment.
- Integrate EUDR reference numbers as a mandatory field in existing ERP or compliance systems and firmly anchor their management in goods receipt, invoicing and archiving.
Conclusion
Correct classification as a market participant or dealer is crucial; errors in this regard have legal consequences. SMEs benefit from simplified requirements but must continue to document declarations of due diligence and reference numbers in an audit-proof manner.
For corporate groups, each legal entity counts individually, not the group as a whole. That is why coordination with legal and compliance departments remains important; an authorized representative (Art. 6 EUDR) can consolidate the burden across the entire group.
Clear roles, regular threshold checks, and effective systems for managing reference numbers form the foundation for legally compliant EUDR compliance.
Frequently asked questions
As soon as a company, together with its affiliated companies, exceeds the thresholds defined in Recommendation 2003/361/EC, it loses its status as an SME for the EUDR. This means that, as a trader, it must carry out the due diligence obligations and any risk analyses itself and can no longer benefit from the simplifications.
Yes, when assessing the SME thresholds, foreign companies are also to be considered together with the subsidiary based in the EU, provided that they are affiliated companies within the meaning of EU law. The consolidated values of the entire group are always used.
With a good system for collecting, managing, and archiving EUDR reference numbers, SME retailers can demonstrate to regulatory authorities at any time which statement of due diligence their products are based on. This helps prevent penalties and makes it much easier to meet the burden of proof.
The EUDR itself does not provide for any transitional periods: The requirements will come into force from December 30, 2026 due to several postponements of the EUDR. Companies should therefore review their structures at an early stage and make the necessary adjustments in order to be legally compliant from this date.
The authorities of the EU member states monitor and enforce the EUDR. They may conduct audits, spot checks, and inspections, and may require companies to provide complete documentation, such as due diligence statements, reference numbers, and other supporting evidence. Violations may result in fines or other penalties.
Simplified requirements apply to small businesses under the EUDR. A business is considered an SME if, under the Accounting Directive 2013/34/EU, it does not exceed at least two of the following three thresholds: €25 million in total assets, €50 million in net revenue, and 250 employees. SME merchants are not required to submit their own due diligence statement; they need only document and archive the market participant’s reference number. For small businesses, the EUDR requirement does not take effect until June 30, 2027—provided they were already classified as small or micro businesses as of December 31, 2024.
Karim Boukaouche
LinkedInESG compliance expert - lawcode GmbH
Karim Boukaouche advises companies on the implementation of the EU Deforestation Regulation (EUDR) and supports the implementation of digital solutions for legally compliant supply chains. His specialist articles on the lawcode blog combine regulatory depth with practical recommendations for action.