 DE

Important facts
- Does the EUDR also apply to packaging made of paper or cardboard?
- No, if they are only used to support, protect, or carry another product. This also applies to reusable and used packaging. In the case of repairs, only the newly added wooden parts are subject to the EUDR. Yes, if packaging is imported or distributed as a standalone product.
- Are POS displays and advertising materials also affected?
- Yes, if they are placed on the market as independent products (e.g. display, POS material as goods) and fall under Annex I as relevant wood or paper products.
- Do instructions for use and brochures have to be taken into account?
- Generally, no: Printed products (HS 49) are not subject to the EUDR. Manuals and similar materials are also exempt if they are merely included with a shipment or provided free of charge for marketing or informational purposes. This exemption is expressly provided for in the draft Delegated Act.
- What needs to be documented?
- Whether the products are deforestation-free and legal, including raw material origin, risk assessment and due diligence declaration (DDS).
- Are digital instructions affected by the EUDR?
- No. Pure digital content such as PDFs or websites are not recorded; physical products from the recorded product groups are relevant.
Executive Summary
The EUDR will apply to large and medium-sized enterprises from December 30, 2026, and to most micro and small enterprises from June 30, 2027 (with exceptions, e.g. for actors already covered by the EUTR). It places special requirements on wood and paper-based products such as packaging and POS displays if they are placed on the market as stand-alone products and fall under Annex I.
Pure protective or carrier packaging, on the other hand, is generally exempt. Pure protective or carrier packaging is generally exempt. Traditional printed matter (HS 49) has been removed from Annex I and therefore generally no longer triggers an EUDR obligation. However, anyone who imports or makes relevant products available as standalone goods must demonstrate their legality and that they are free from deforestation and file a due diligence statement in the EU information system.
Companies should identify affected product groups at an early stage, check supply chains and establish clear internal processes to minimize compliance risks.
Never miss an update on the EUDR again.
New specialist articles, regulatory updates and practical tips, straight to your inbox. Once a week, no spam.
To which products does the EUDR apply?
The EUDR is intended to ensure that certain raw materials and products made from them do not contribute to deforestation or forest degradation when placed on the market within the EU. The obligations will apply from December 30, 2026 for large and medium-sized enterprises and, in principle, from June 30, 2027 for micro and small enterprises. Only the raw materials defined in the regulation and the relevant products made from them in accordance with Annex I (CN/tariff codes) are affected.
To this end, companies must fulfill their due diligence obligations: They assess risks and demonstrate that the relevant products are legal and deforestation-free. The relevant raw materials include beef, cocoa, coffee, oil palm, rubber, soy, and wood.
What the EUDR regulates and what it does not
The EU Deforestation Regulation applies to a clearly defined list of raw materials and products (Annex I). This list is based on the EU Customs Tariff codes (CN/HS). It primarily covers products derived from cattle, wood, cocoa, coffee, soy, oil palm, and rubber, as well as certain products manufactured from them, which are also listed in Annex I.
Important: Not every product made of paper or wood automatically falls under the EUDR. The specific product type, the classification according to the CN code and the functional context are always decisive. In addition, there is a key clarification from the FAQs and the current drafts of the delegated act: packaging material that is used exclusively to support, protect or carry another product is not considered a "relevant product", regardless of the HS code.
At the same time, the scope of application has recently changed noticeably: Certain printed products ("ex 49") have been removed from Annex I. This means that classic printed products (e.g. many brochures or printed products as such) are no longer the typical "scope trigger" under the EUDR.
→ As a guide, the safest way to classify them is therefore via Annex I + CN Code, supplemented by the FAQ clarifications of the European Commission, which are updated regularly.
Does packaging fall under the EUDR? Packaging as a Special Case
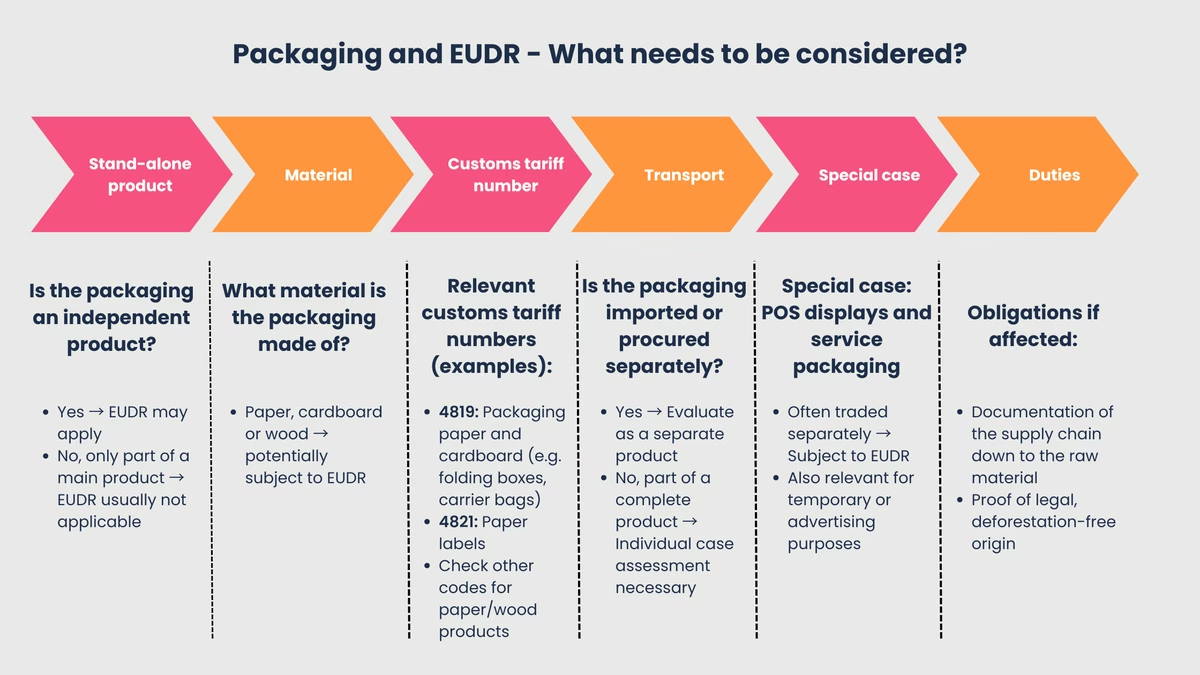
Packaging is a special case within the framework of the EUDR and is often difficult to classify in practice. Whether they actually fall under the regulation depends not only on whether they are traded as independent products, but above all on their function in the specific flow of goods: Is the packaging placed on the market as a product "in its own right" (stand-alone/empty) or is it used exclusively to support, protect or carry another product?
According to the current FAQ/guidance line and the draft of the delegated act:
- Packaging material is not subject to the EUDR if its sole purpose is to support, protect, or carry another product. This applies regardless of the CN/HS code, including for paper or cardboard packaging.
- Packaging is subject to the EUDR if it is sold as a product in its own right—that is, if it does not merely enclose another product but is sold separately. Examples include empty folding boxes, shopping bags, or gift boxes that are purchased individually.
In practice, commodity codes such as:
- 4819: Paper/cardboard packaging (e.g. folding boxes, carrier bags)
- 4821: Paper labels (see note below)
- as well as other customs tariff numbers for wood and paper products, whereby the function ("standalone" vs. "only packaging for another product") overrides the scope question in many cases.
Important Note on Labels: Labels that are merely included with a product or provided free of charge for marketing or informational purposes are not subject to the EUDR. This also applies to instruction manuals, flyers, and catalogs. This is based on a specific exemption in the draft Delegated Act (as of May 2026). Labels are subject to the EUDR only if they are sold as a commercial product in their own right—for example, unprinted label rolls sold as a standalone product.
It remains particularly tricky with service packaging and POS displays. If these are produced and procured separately and placed on the market as independent goods, they may be subject to EUDR, depending on the material and classification in Annex I.
Three questions are key to the assessment: What is the material's tariff code (CN/TARIC)? What function does it serve? And is it sold on its own, or does it serve solely as packaging for another product?
The operational test: joint or separate customs classification
Anyone who needs to decide whether packaging is “self-contained” or merely protective or supportive should rely on a clear legal rule of thumb, not on how the invoice is formatted. The classification according to the General Rules for the Interpretation of the Combined Nomenclature is decisive.
- General Rule 5a distinguishes between two cases: If the container gives the product its “essential character,” it is classified on its own. In that case, it is potentially subject to the EUDR. If, on the other hand, the container is specifically designed for a product, is durable, and is usually sold together with the product (e.g., a jewelry box or an instrument case), it is considered part of the product. In that case, it is not subject to the EUDR.
- General provision 5b clarifies: Ordinary packaging materials that are presented with the goods and correspond to the usual packaging of these goods are classified together with the product for customs purposes and are therefore not to be treated as a separate relevant product within the meaning of the EUDR. According to the Guidance, this also expressly applies to wrapping and wrapping material made of paper, provided it is used to protect, carry or transport another product.
The practical consequence: Whether the packaging is shown separately on the invoice or not is irrelevant for the EUDR classification. The only decisive factor is whether it would be classified together with or separately from the goods under customs law in an import or export scenario. If the classification were joint, the packaging is considered "support, protect, carry" material and is not within the scope of application - regardless of the HS code.
Note for adjacent materials: Due to the latest amendments (ex 49), classic printed products are no longer the typical "scope trigger" in the EUDR context.
Are instructions and user manuals subject to EUDR?
Paper-based product manuals and instructions for use are included with almost every technical or electrical device. Many companies wonder: Do these accompanying materials fall under the EUDR, even though they are often perceived as only a small part of the packaging? Correct classification is important to avoid legal risks resulting from incorrect classification.
Paper-based instructions - what currently applies?
Many instructions, installation instructions or warranty cards consist of printed paper and are therefore generally considered to be printed products. However, the decisive factor for the EUDR is whether a product is even included in Annex I as a 'relevant product'. This is no longer the case for traditional printed products. Printed products ("ex 49") are no longer the typical connecting factor for the EUDR, meaning that classic printed products such as brochures, leaflets or manuals should no longer be classified as subject to the EUDR across the board.
In practice, this means that product manuals, inserts, or warranty cards that are merely included with a shipment generally do not trigger a separate EUDR obligation. This is especially true if they are not traded separately—that is, if they are not sold or imported as standalone print products.
Check exception: Is it "correspondence"?
The EUDR also includes an exception for “correspondence.” This refers to shipments intended solely for communication purposes, such as personally addressed letters, notices, or similar business mail. Such shipments are not considered “placing on the market” of a relevant product and are therefore generally not subject to the EUDR.
In practice, however, this remains a marginal case: most inserts (e.g. standard instructions, warranty cards, assembly instructions) are not individually addressed, but mass-produced goods. At the same time, the framework has recently changed: Printed products ("ex 49") are no longer the typical scope link, meaning that these materials are now much less likely to be EUDR-relevant "on their own".
Marketing and information material: separate exception in the delegated act
The draft delegated act (as of May 2026; consultation period ends June 1, 2026) provides an important clarification. According to the draft, certain materials are not covered by the EUDR: user manuals, flyers, catalogs, and labels. The condition is that they are merely included with another product or provided free of charge for marketing or informational purposes.
This exception is important because it goes beyond the HS 49 exemption. It also applies to materials from other chapters, such as paper labels (HS 4821), which do not fall under Chapter 49 for customs purposes but serve the same informational or marketing purposes.
Practical consequence
Labels that are included with or affixed to a product do not normally trigger an EUDR obligation in and of themselves. Labels are only subject to EUDR requirements if they are sold as commercial goods in their own right—for example, blank label rolls that a printing service provider or label manufacturer offers separately as merchandise.
Disclaimer: The delegated act has not yet been formally adopted. Companies should therefore initially mark the classification as “expected to be out of scope.” They should not make any final adjustments to their compliance processes until the act has been published in its final form in the Official Journal.
Ready for the EUDR launch?
With our EUDR module, you can capture geographic data, analyze risks, and create due diligence statements digitally and efficiently—instead of wading through spreadsheets.
Sales packaging, displays and POS materials
Not only secondary packaging, but also POS (point of sale) materials, sales displays and marketing materials are traded across borders as part of modern goods logistics. The extent to which these fall under the EUDR depends on their material composition, their function and their individual tariff classification.
Sales packaging - what does it include?
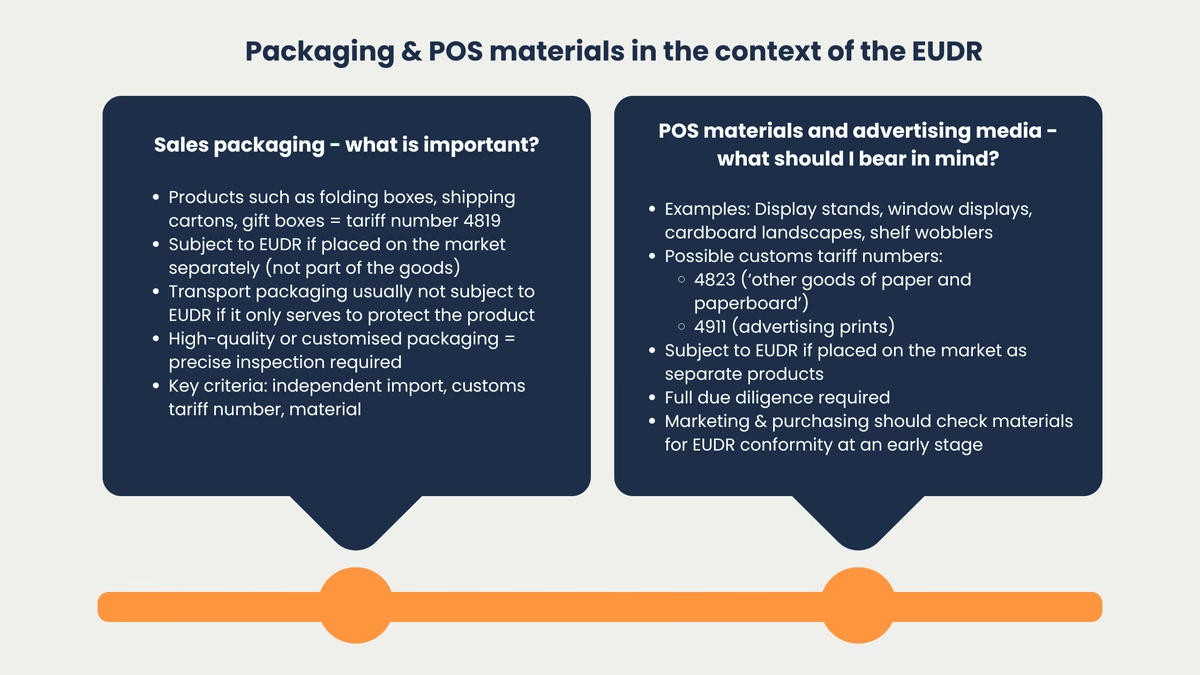
We encounter sales packaging every day: from folding cartons for food to shipping boxes and elaborate gift boxes. In the customs tariff, packaging made of paper, cardboard and paperboard is often classified under 4819 (e.g. folding boxes, cartons, carrier bags). However, the decisive factor for the EUDR is not just the goods code, but how the packaging is used and provided in the actual flow of goods.
According to the current FAQ/guidance line and the draft delegated act, packaging material that is used exclusively to support, protect or carry another product is not covered by the EUDR, regardless of the HS/CN code under which it is classified. In practice, this applies to typical sales and shipping packaging that is delivered together with the goods and does not have the character of goods in its own right.
Packaging, however, becomes subject to the EUDR when it is placed on the market, imported, or distributed on its own—that is, when it is empty. This is the case, for example, when a company buys or sells empty folding cartons, gift boxes, or other packaging components as separate items.
Reusable and repaired packaging: Special cases of EUDR application
The EUDR makes a clear distinction: If packaging material is marketed as a standalone product, it falls under the regulation. If, on the other hand, it serves only to support, protect, or carry another product, it does not fall under the regulation. Recent FAQs and draft delegated acts have further clarified this exception and extended it to reusable packaging as well.
The European Commission’s Guidance Document (2026) makes an important operational distinction here:
- Disposable packaging (single use) is not within the scope of application as soon as it is presented with the goods and used exclusively to support, protect or carry another product.
- Reusable packaging (repetitive use) is excluded from the scope of application from the moment it is first used to support, protect or carry another product - and from then on. Specifically, a pallet that has entered the EU under load remains exempt even if it is subsequently resold empty, rented out or made available again within a pallet pool or closed-loop system.
- Repairs to packaging: If used packaging (that previously supported, protected, or carried another product) is repaired with new wooden parts and then sold, the EUDR applies only to the newly added parts.
POS displays and advertising materials made of paper
POS materials are marketing materials used at the point of sale, such as freestanding displays, window displays, shelf wobblers, or cardboard displays. They are becoming increasingly important in the retail sector and are often made of printed cardboard, sturdy corrugated cardboard, or wood.
Whether these products fall under the EUDR depends on two points in particular:
- Are they marketed as standalone products?
- Do they fall under a product category listed in Annex I with their specific classification?
A recent clarification is important here: materials that are used exclusively to support, protect or carry other products are not considered "relevant products" - regardless of the CN code. This can play a role for certain POS solutions in particular, if they are functionally more likely to be classified as a carrier/packaging solution.
In practice, POS displays made of paper/cardboard are often listed under product codes from Chapter 48 (e.g. "other articles of paper and paperboard" such as 4823, depending on the specific design). Advertising prints as a separate product category (Chapter 49, e.g. 4911), on the other hand, are no longer the typical scope link, as printed products ("ex 49") have been removed from Annex I.
Here’s an example: An international electrical appliance manufacturer has large-format displays made of printed cardboard produced and rolled out to its stores as part of its market entry strategy. If such displays are procured and provided as standalone products, companies should do two things: clearly document their classification using Annex I and the CN code, and establish the appropriate EUDR processes (due diligence, supporting documentation, and, if necessary, a declaration of due diligence/DDS).
Catalogs, brochures and assembly instructions
Not only packaging, but also inserts, information materials and technical accompanying documents cause uncertainty in practice. However, the decisive factor is that the EUDR is linked to "relevant products" in accordance with Annex I (CN/customs tariff codes) and the framework here has recently changed. Printed products ("ex 49") are no longer part of Annex I, which is why classic printed products are now generally not to be treated as independent EUDR-relevant goods.
Catalogs and advertising brochures
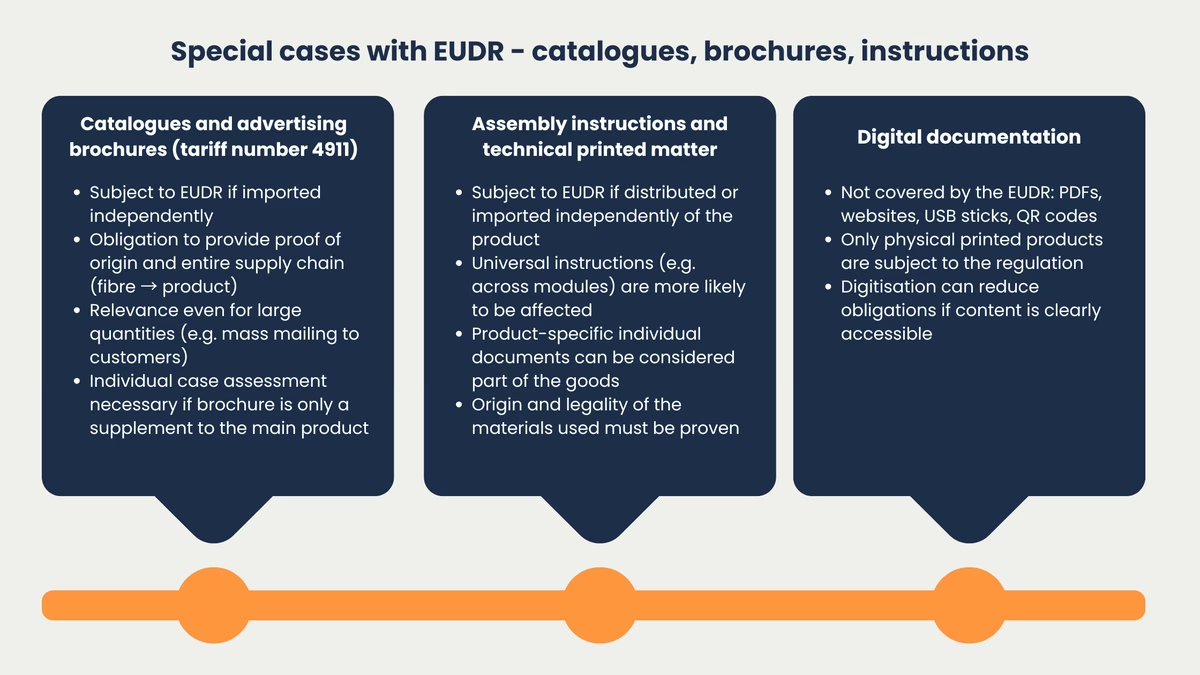
Catalogs, brochures and advertising brochures are often classified under 4911. This classification has long been a frequent trigger for EUDR discussions. Currently, however, it is no longer the relevant "scope trigger", as printed products ("ex 49") have been removed from the annex.
To Do:
For companies, this means that although advertising materials such as catalogs or brochures should continue to be properly tariffed and documented, they are no longer generally subject to EUDR solely because of their printed product character. Instead, the cases in which other covered paper/wood products (e.g. certain packaging or paper products from Chapter 48) are placed on the market as separate goods will become more relevant.
Assembly instructions
In practice, assembly instructions, assembly aids or technical drawings are usually also classic print products. This also applies here: As purely printed documents, they are typically no longer the central EUDR use case.
Another important point regarding delivery practices: Documents that are merely included with a shipment of goods (e.g., standard instructions inside a box) are normally covered by the exception for accompanying materials. This applies provided that they are not marketed as standalone goods or traded separately.
What about digital documentation?
Digital documentation (PDF, online manual, QR code link) is not covered by the EUDR - the regulation is aimed at physically relevant products. Consistent digitalization can therefore help to reduce complexity in the accompanying material.
For physical data storage media (e.g., USB flash drives), the same rule applies as before: It is not the stored data that is relevant, but only whether paper or wood components are placed on the market as standalone products.
Recommendations for companies
The classification and implementation of EUDR obligations is challenging, especially for companies with complex or international supply chains. A proper risk analysis and effective internal processes are key for manufacturers, importers and distributors. It is important to note that the EUDR is linked to "relevant products" in accordance with Annex I (CN/customs tariff codes) and the framework has recently changed in certain areas (e.g. deletion of printed products "ex 49").
Which areas are affected?
The EUDR primarily applies to companies that independently import, manufacture, store, or sell wood- or paper-based products. Examples include packaging, labels, point-of-sale displays, and certain paper and cardboard products. These products must fall under Annex I.
At the same time, a key clarification from the FAQs applies: materials that are used exclusively to support, protect or carry another product (support/protect/carry) are not to be treated as a "relevant product" - regardless of the CN/HS Code. In practice, this applies to many typical shipping and sales packaging as well as accompanying materials that only "accompany" the product.
Establish internal testing processes
Companies should implement a clear inspection process that systematically evaluates all affected items, ideally integrated into existing quality, customs, or audit procedures. In practice, three inspection steps have proven effective:
- Classification (CN/TARIC code + material)
- Function allocation (standalone product or only support/protect/carry)
- Comparison with Annex I and documentation of the decision.
DDS & information system: implementation is now a data process
For relevant products, companies must organize the due diligence information in such a way that it can be incorporated into a due diligence statement (DDS). This includes, among other things, details such as product/CN code, quantity, country of origin, and, depending on the goods, geolocation data.
Submissions and administration are handled through the European Commission’s information system. It is already live and will continue to be developed until the regulation is fully implemented. Planned features include simplified reporting options and the registration of new roles, such as for micro- or small operators, as well as for downstream market participants (downstream non-SME operators or traders).
Expand supplier documentation
Many companies rely on information from their suppliers. That is why buyers should regularly request the necessary EUDR documentation and keep it up to date. This applies in particular to items that are sold independently, such as empty packaging, point-of-sale (POS) materials, or labels sold as separate products. This requires a standardized set of data that meets the requirements of the Due Diligence Statement (DDS), including geolocation information when necessary.
To Do:
Check for each product: Does it fall under Annex I? Is it placed on the market as an independent product or is it only used as protective or carrier packaging? Only those who answer these three questions clearly will achieve legally compliant EUDR compliance.
Excursus: Chain of custody certificates
Chain-of-custody certificates (CoC) prove the complete traceability of a raw material - such as wood or paper - along the entire supply chain, from its origin to the finished product. They confirm that the material comes from a certified, legal source and has not been mixed with non-certified raw materials during processing and trade. In the context of the EUDR, chain of custody certificates can help to fulfill the required duty of proof and due diligence.
Under the EUDR, mass-balance CoC systems that mix deforestation-free raw materials with raw materials of unknown origin or that are not deforestation-free are expressly prohibited. Such systems cannot guarantee that the products sold on the EU market are truly deforestation-free. Therefore, raw materials must be kept separate at every stage of the supply chain.
Conclusion
Not everything made of wood or paper automatically falls under EUDR. The decisive factors are Annex I, the correct CN/TARIC classification and the functional relationship. If the material is used exclusively as protective or carrier packaging, it is generally not covered. Classic printed products (HS 49) are also no longer within the scope of application.
Companies should now check all wood and paper products they have imported or sold on their own against Annex I. Data and supporting documentation should be prepared in such a way that they can later be incorporated directly into a due diligence statement (DDS).
The time remaining until December 30, 2026—and until June 30, 2027, for most micro and small businesses—should be used effectively to this end. Those who prepare early reduce compliance risks and avoid supply disruptions.
Frequently asked questions
All packaging made of paper, cardboard, paperboard or wood that is placed on the market or imported as independent goods is affected. This includes sales packaging, shipping cartons and often also promotional packaging. Pure transport packaging is not always subject to EUDR if it is an integral part of another product and not a product in its own right.
POS displays and advertising materials made of paper, cardboard or wood are affected by the EUDR as soon as they are produced, imported or distributed as independent goods. Companies should check the relevant product group and customs tariff number and keep the necessary proof of the supply chain.
Yes, if instructions for use, assembly instructions or other accompanying documents are listed as separate goods, they are affected by the EUDR. Examples include components of a set or separate brochures. If they are non-individual, mass-produced instructions, they are regularly subject to EUDR.
Digital manuals and digital instructions on websites, apps or data carriers are not covered by the EUDR. Only physically existing printed works and paper products are affected by the EU Deforestation Regulation. Companies can therefore partially reduce their impact by changing their media.
Proof must be provided for all stages of the supply chain, from fiber production to the end product. This includes confirmations from suppliers, chain-of-custody certificates and proof of origin. Regular updating and integration of all evidence into internal compliance processes is recommended to ensure legal security for all packaging and POS materials.
Generally no: Printed products (ex 49) have been removed from the scope and the draft Delegated Act 2026 adds an explicit marketing/information material exemption, which also includes labels. Manuals and similar material that only accompany a consignment are thus excluded from the scope."
Karim Boukaouche
LinkedInESG compliance expert - lawcode GmbH
Karim Boukaouche advises companies on the implementation of the EU Deforestation Regulation (EUDR) and supports the implementation of digital solutions for legally compliant supply chains. His specialist articles on the lawcode blog combine regulatory depth with practical recommendations for action.